ESOPs Meaning: Full Form, How They Work and Where They Fit in Total Rewards
What ESOP stands for and how ESOPs actually work: vesting, exercise price, ESOPs vs RSUs, and how equity shows up in your total rewards.
Quick answer:
ESOP stands for Employee Stock Option Plan. It gives you the right, not the obligation, to buy shares in your company at a fixed price set on the day the options were granted. According to NCEO's 2026 data, US employee ownership plans hold $2.1 trillion in assets, covering 15.1 million employees. Yet Salary.com's 2026 State of Pay report found that only 46% of organisations show employees a complete total rewards statement, which means most people holding ESOPs have no real sense of what those options are worth today. This guide covers the mechanics, the common mistakes, and how to read an ESOP grant for what it is actually telling you.
You get an offer letter. It mentions ESOPs. Maybe you nodded. Maybe you Googled it that night and came away more confused than when you started. That is not unusual. ESOPs are one of the most commonly offered and least understood forms of compensation on the market today.
Part of the confusion is that "ESOP" gets used loosely. The full form is Employee Stock Option Plan. In some US contexts you will also see it written as Employee Stock Ownership Plan, a different structure. In startup and growth-stage company compensation globally, ESOP almost always refers to Employee Stock Option Plans, which is what this article covers.
What follows is a plain-language breakdown of how ESOPs work, what the key terms actually mean, how they compare to RSUs, and how to evaluate a grant when you are looking at one in an offer letter or an annual review.
How ESOPs work: the 4-stage journey
Every ESOP grant moves through the same four stages. Understanding each stage is the difference between knowing what you have and guessing what you have.
Stage 1: Grant
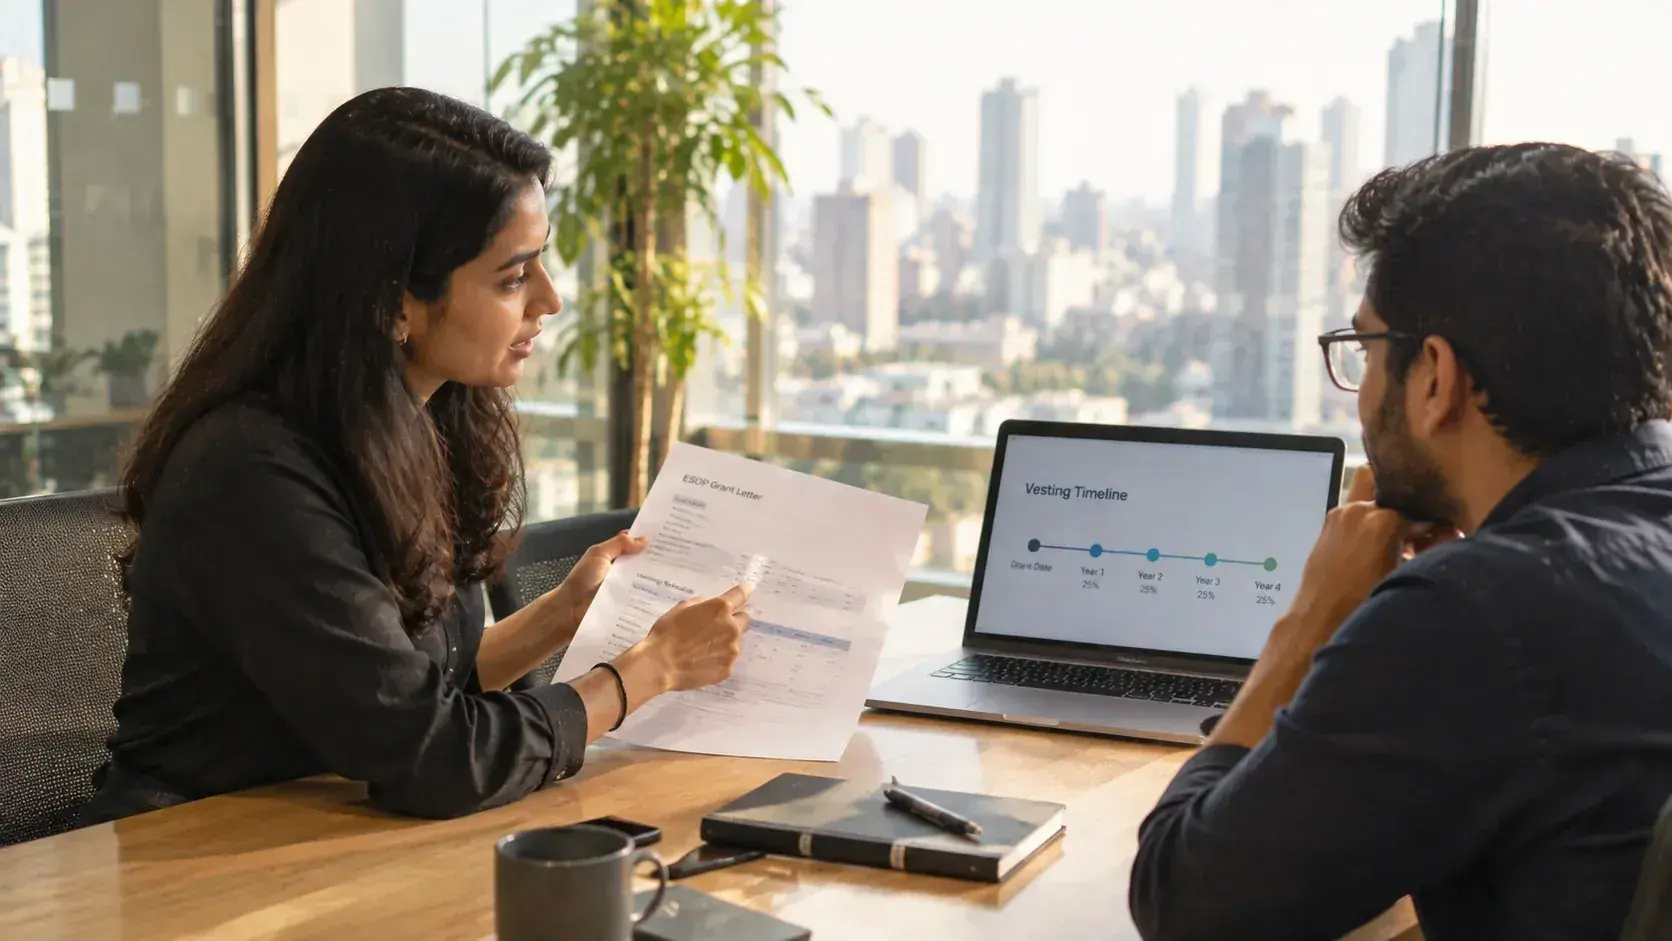
The company grants you a certain number of stock options. Your Grant Letter documents how many options you received, the exercise price per share, the vesting schedule, and the expiry date. Read this letter. Most employees do not. The details buried in it, particularly the post-termination exercise window and the cliff date, are the ones that catch people by surprise years later.
No tax is triggered at grant. The grant is simply a documented promise of future ownership, not actual ownership and not actual money.
Stage 2: Vesting
Vesting is how options become yours over time. Most ESOP grants follow a standard structure: 4-year vesting with a 1-year cliff.
Year | Vesting event | Cumulative options vested |
|---|---|---|
End of year 1 | 25% vests (the cliff) | 25% |
Year 2 (monthly) | Approximately 2.08% per month | 50% |
Year 3 (monthly) | Approximately 2.08% per month | 75% |
Year 4 (monthly) | Approximately 2.08% per month | 100% |
Caption: Standard 4-year vesting with a 1-year cliff, the common industry structure for ESOP grants.
The cliff means nothing vests for the first 12 months. Leave before your first anniversary and you walk away with zero options from that grant, regardless of how many months you worked. After the cliff, vesting continues monthly until the 4-year mark.
Some companies use performance-based vesting, accelerated vesting clauses, or different cliff structures. The grant letter is the authoritative document. Do not rely on what someone told you at onboarding.
A concrete example: Priya joins a Series B startup and receives 1,000 ESOPs with a 4-year vest and 1-year cliff. On her 1-year anniversary, 250 options vest. From month 13 onwards, approximately 20.8 options vest each month. By the end of year 4, all 1,000 are hers to exercise.
Stage 3: Exercise
Once options vest, you can choose to exercise them by paying the exercise price, also called the strike price, to actually buy the shares. The exercise price was set on the day your options were granted and never changes. If the company's fair market value (FMV) has risen since then, you are buying at a discount. That difference between FMV at exercise and your exercise price is your spread, and that is where the value lives.
Component | Value |
|---|---|
Exercise price (grant date) | Rs.100 per share |
Fair market value at exercise | Rs.800 per share |
Spread (gain per share) | Rs.700 per share |
1,000 shares exercised | Rs.7,00,000 total paper gain |
Caption: Illustrative example only. Actual values depend on company growth and individual grant terms.
In most countries, tax is triggered at exercise. The spread is typically treated as salary income and taxed at your applicable rate. This creates what is sometimes called the exercise tax trap: you owe tax on a gain you have not yet converted to cash. Before you exercise, model the tax liability. In India, employees of eligible startups certified under Section 80-IAC can defer the tax at exercise, typically until the shares are sold, they leave the company, or a set period passes (source needed).
AI in Total Rewards: how AI is changing ESOP modelling and valuation. Most employees have historically received a grant letter and a static projected value with no way to update those projections as the company's valuation changed. AI-driven total rewards platforms now offer real-time ESOP modelling: they pull current FMV from 409A valuations or board-approved share prices, apply your specific vesting schedule, and calculate what your options are worth today under different exit scenarios.
This matters particularly at the exercise stage. The decision to exercise vested options involves a tax calculation, a liquidity timing judgment, and an assessment of company trajectory, all simultaneously. Platforms that automate this modelling and surface it alongside salary and benefits data give employees the information they need to make that decision without relying entirely on their own spreadsheet skills or an expensive financial advisor.
Stage 4: Sale
Once you have exercised and own shares, you can sell them when a liquidity event occurs: an IPO, acquisition, company buyback, or an approved secondary sale. Any profit between your exercise FMV and the eventual sale price is typically treated as capital gains and taxed separately from the exercise tax you already paid.
Key ESOP terms
These ten terms appear in virtually every ESOP conversation. Knowing them is what makes a grant letter readable rather than impenetrable.
Term | What it means |
|---|---|
Grant | The initial allocation of options to an employee, documented in a grant letter |
Exercise price / strike price | The fixed price per share you will pay to buy shares, set on the grant date and never changed |
Fair market value (FMV) | The current assessed value of one share at any point in time, used to calculate your gain |
Vesting | The process by which options become exercisable over time, usually tied to tenure or performance |
Cliff | A minimum waiting period, usually 1 year, before any options vest at all |
Exercise | The act of paying the exercise price to convert options into actual shares |
Spread | The difference between FMV at exercise and your exercise price. This is your paper gain per share |
Liquidity event | An event (IPO, acquisition, buyback) that allows you to convert shares into actual cash |
Expiry | Options have an expiry window, usually 10 years from grant or shorter after leaving. Unexercised options after expiry become worthless |
Cap table | The complete record of who owns how much equity in the company, where your ESOP allocation lives |
[Upload image: esops-grant-review.webp | Alt: A woman at an office desk reviewing printed figures with a calculator.]
ESOPs vs RSUs vs ESPPs
When your employer talks about equity compensation, they might use ESOPs, RSUs (Restricted Stock Units), or ESPPs (Employee Stock Purchase Plans). These are not the same thing.
Feature | ESOPs | RSUs | ESPPs |
|---|---|---|---|
What you receive | Right to buy shares at a fixed price | Shares granted free on vesting | Right to buy shares at a discount |
Cost to employee | Must pay exercise price | Nothing, shares are free | Usually 5 to 15% below market price |
Value if stock drops | Can go underwater and become worthless | Always has some value | Minimal risk: you buy at a discount |
Risk level | Higher, depends on share price growth | Lower: always worth something | Low, discount protects downside |
Tax trigger | At exercise (most jurisdictions) | At vesting (most jurisdictions) | At purchase and/or sale |
Best suited for | Startups and high-growth companies | Listed companies and scale-ups | Public companies with stock plans |
Typical vesting | 4 years with 1-year cliff | 1 to 4 years, sometimes quarterly | Purchase periods of 6 to 24 months |
Caption: Source: MEQ Law, Carta, TreeLife RSU vs ESOP comparison, 2026.
There is no single right answer on which is better. ESOPs offer more potential upside if the company grows significantly. RSUs offer more certainty because you will always receive something of value. Startups typically offer ESOPs because they conserve cash. Larger listed companies tend to offer RSUs because they are simpler to communicate and immediately valuable. If you are joining an early-stage company with high growth potential, ESOPs can be significant. If you are joining a public company, RSUs are likely more predictable and easier to plan around.
AI in Total Rewards: AI-powered equity comparison tools for offer evaluation. Evaluating an ESOP offer against an RSU offer from a different company has traditionally required a financial model, tax knowledge, and assumptions about growth trajectories that most candidates do not have time to build. AI tools embedded in modern compensation platforms now run this comparison automatically: they take the grant parameters from both offers, apply jurisdiction-specific tax rules, and model expected value across a range of exit scenarios and timelines.
For HR teams, this matters at the offer stage. Candidates increasingly ask sophisticated questions about equity value relative to cash, particularly when they are comparing offers from a startup and a listed company. Teams that can produce a clear, modelled comparison of their equity offer against market norms close more offers and spend less time in back-and-forth negotiation about grant details that neither side has fully calculated.
How ESOPs show up in total rewards
Here is something most employees do not realise: companies often invest considerably more than your base salary in your total compensation package, and ESOPs are frequently the largest single component of that invisible investment (source needed).
When you think your salary is Rs.20 lakhs, the company may actually be investing Rs.26 to Rs.28 lakhs in you annually once you factor in ESOPs, benefits, insurance, bonuses, and recognition. Almost nobody shows employees this full picture. According to Salary.com's 2026 State of Pay report, only 46% of organisations show employees a complete total rewards statement, which means more than half of all employees are valuing their compensation based on base salary alone.
A total rewards statement with ESOPs
Compensation component | Annual value (illustrative) | % of total |
|---|---|---|
Base salary | Rs.18,00,000 | 64% |
Performance bonus (target) | Rs.2,70,000 | 10% |
ESOP grant value (annualised) | Rs.4,50,000 | 16% |
Health insurance (employer contribution) | Rs.90,000 | 3% |
Provident Fund (employer contribution) | Rs.1,08,000 | 4% |
Learning and wellness budget | Rs.60,000 | 2% |
Recognition and spot awards | Rs.30,000 | 1% |
Total annual investment | Rs.28,08,000 | 100% |
Caption: Illustrative example only. ESOP value is annualised based on current FMV minus exercise price divided by vesting period. Actual values vary by company and grant.
The ESOP grant in this example contributes Rs.4.5 lakhs of annual value, more than the health insurance, PF, and every other benefit combined. Yet in most companies, employees only see the Rs.18 lakh base salary number and form their entire perception of their package around that.
"The ESOP grant contributing 16% of total compensation sits invisible in a grant letter nobody reads twice. The visibility gap is not a technology problem. It is a design decision that companies have not made yet."
This visibility gap drives misaligned expectations, "I feel underpaid" conversations that are not actually about pay, and attrition that could have been avoided if employees had simply seen the full picture. The companies closing this gap are the ones giving employees total rewards statements that show every component, including equity value modelled across vesting scenarios.
Why companies offer ESOPs
ESOPs are not charity. Companies offer them for specific strategic reasons, and understanding those reasons helps you evaluate your own grant more clearly.
Company motivation | What it means for you |
|---|---|
Conserve cash | Instead of paying higher salaries, companies offer future equity. Your ESOP is partially a substitute for cash compensation. The tradeoff: more risk, potentially more upside |
Align employee interests | When you own a stake in the company's success, you are more likely to act like an owner. ESOPs are designed to create this alignment |
Attract talent without high cash burn | Early-stage companies can compete with larger companies for talent by offering equity upside instead of matching market salaries |
Retain key employees | The vesting cliff and schedule create financial incentives to stay with the company long enough to earn your options |
Facilitate succession | In some structures, ESOPs transfer ownership from founders to employees over time, common in employee-owned businesses |
How big ESOPs are globally
ESOPs are not a niche instrument. They are a mainstream compensation vehicle with significant global scale. The US figures below are for Employee Stock Ownership Plans, the retirement-trust structure, rather than stock option plans.
Statistic | Data point | Source |
|---|---|---|
US ESOP participants (2026) | 15.1 million employees | NCEO, 2026 |
US companies with ESOPs | 6,411 companies | NCEO, 2026 |
Total US ESOP assets | $2.1 trillion | NCEO, 2026 |
% of ESOPs in private companies | Over 90% | NCEO, 2026 |
Growth in Total Rewards roles | 60% increase since 2018 | WorldatWork, 2026 |
Companies with no total rewards statement | 54% of organisations | Salary.com, 2026 |
Caption: Sources: NCEO Statistical Profile 2026; Rutgers University April 2024; WorldatWork 2026; Salary.com 2026 State of Pay Report.
5 common ESOP mistakes
Understanding ESOPs is one thing. Navigating them well is another. Here are the five mistakes that cost employees the most in real terms.
Mistake 1: Leaving before the cliff
This is the most expensive mistake in ESOP history. Leaving before your 1-year cliff means forfeiting every option in your grant, even if you worked there for 11 months and three weeks. Always factor your cliff date into any decision to resign or accept a competing offer. Check whether the new offer has any cliff-crossing provisions or accelerated vesting language.
Mistake 2: Not reading the grant letter
Your grant letter contains the exercise price, vesting schedule, expiry date, and post-termination exercise window. Many employees never read it past the first paragraph. The post-termination exercise window is where significant value gets lost: some companies offer 90 days, others offer 1 to 10 years. That difference matters enormously if you leave before a liquidity event. Read the letter. Ask HR if anything is unclear before you need to use it in a time-sensitive situation.
Mistake 3: Assuming ESOPs will definitely be worth something
ESOPs are valuable only if the company's shares are worth more than your exercise price when you exercise. If the company does not grow, or if you exercise at a moment when the share price is lower than your exercise price, the options are underwater and worthless. Equity is not a guarantee. It is a bet on the company's future, weighted by how much of the company that equity represents.
Mistake 4: Ignoring the tax at exercise
In most countries, exercise triggers a tax event on the spread. This can be a significant cash liability, sometimes larger than the cash you have available. Know your jurisdiction's rules before you exercise. In India, employees of eligible startups certified under Section 80-IAC can defer the tax at exercise (source needed). Always verify whether your employer qualifies before assuming you have this option.
Mistake 5: Forgetting the exercise window after leaving
When you leave a company, you typically have a short window, often 90 days, to exercise your vested options. After that, they expire and become worthless. Some companies offer extended exercise windows of 1 to 10 years. Many employees have lost significant value by missing this deadline because they assumed the options would remain available indefinitely. Check your post-termination window before you hand in notice, not after.
AI in Total Rewards: AI tools for ESOP communication and employee education. The five mistakes above share a common root: employees receiving a grant letter they cannot interpret, with no follow-up education and no tool to model what the options might be worth under different scenarios. AI-powered total rewards platforms are addressing this at the point of communication rather than after the fact.
The most useful applications: AI chatbots that answer employee ESOP questions in plain language, personalised exercise scenario calculators built into employee self-service portals, and automated cliff and expiry alerts that notify employees before a deadline they would otherwise miss. The 90-day post-termination window is the clearest example where a simple automated alert, sent 60 days after resignation, would save employees significant money at essentially zero cost to the employer.
For HR teams running ESOP programmes across multiple jurisdictions, AI also helps manage the compliance complexity: jurisdiction-specific tax rules, startup tax deferral eligibility in India, qualified vs nonqualified stock option distinctions in the US, and EMI scheme rules in the UK all require different employee guidance. AI layers that surface the right information to the right employee based on their location and grant type are beginning to make this manageable at scale.
How to evaluate your ESOP grant
When you receive an ESOP offer, whether in a job offer or an annual grant, here is a practical checklist for evaluating what it is actually worth.
Question to ask | Why it matters |
|---|---|
How many options am I receiving? | The raw number matters less than the percentage of the company it represents |
What is the exercise price? | Lower is better. A wider spread means more potential gain |
What is the current FMV per share? | Tells you the current paper value of your options if you exercised today |
What is the vesting schedule and cliff? | Determines when and how you earn your equity |
What is the post-termination exercise window? | Critical if you might leave the company before a liquidity event occurs |
What percentage of the company does this represent? | A small % in a large company can be worth more than a large % in a small one |
What is the latest 409A or FMV valuation? | Gives context for whether the exercise price is favourable |
Is there a liquidity plan or IPO timeline? | Determines when you can actually convert options to cash |
Does the company qualify for tax deferral (India)? | Eligible startups certified under Section 80-IAC can offer deferral of the exercise tax |
Frequently asked questions
What is the full form of ESOP?
ESOP stands for Employee Stock Option Plan (or Employee Stock Ownership Plan in certain US contexts). In startup and growth-stage company compensation, ESOP almost always refers to Employee Stock Option Plans, where employees receive the right to purchase company shares at a fixed price in the future.
When do ESOPs actually become valuable?
ESOPs become valuable when two things are true simultaneously: your options have vested, and the company's current share value (FMV) is higher than your exercise price. If either condition is not met, the options either cannot be exercised yet or are not worth exercising. The eventual value is realised at a liquidity event: IPO, acquisition, or buyback.
What happens to my ESOPs if I quit?
Unvested options are forfeited immediately. For vested options, you typically have a limited window, often 90 days, to exercise them before they expire. Some companies offer extended exercise windows of 1 to 10 years, which makes a material difference if there is no immediate liquidity event. Always check your grant letter and company policy before resigning.
Are ESOPs included in my CTC?
In India, ESOPs are frequently listed in CTC calculations, but the way they are valued can be misleading. Some companies use the FMV at grant minus exercise price multiplied by shares. Others use a projected value at a future exit. Always ask how the ESOP component in your CTC is calculated and verify the underlying assumptions. The number shown in a CTC breakdown is a projection, not a guarantee.
How do ESOPs show up in my total rewards?
ESOPs are part of the Long Term Incentive (LTI) layer of your total rewards package, sitting alongside compensation, benefits, insurance, and recognition. A well-designed total rewards statement shows employees the annualised value of their equity grant alongside every other component the company invests in them. When employees can see the full picture, they consistently revise their perception of their total compensation upward.
What is the difference between exercise price and FMV?
The exercise price is the fixed price per share set on your grant date. It never changes. The Fair Market Value (FMV) is the current assessed value of one share. The difference between them is your spread, which is the potential gain per share. If your exercise price is Rs.100 and the current FMV is Rs.900, your spread is Rs.800 per share. That spread is what makes ESOPs valuable, and it only exists if the company has grown since your grant date.