What are ESOPs? ESOP meaning, vesting and tax in India
A plain-English guide to employee stock option plans in India: grant, cliff, vesting, exercise and how ESOPs are taxed at exercise and at sale.
In short: An ESOP (Employee Stock Option Plan) gives an employee the right – not the obligation – to buy a set number of company shares at a fixed price, once vesting conditions are met. In India, ESOPs are governed by the Companies Act, 2013, are not taxed at grant or vesting and are taxed twice: as a salary perquisite at exercise and as capital gains at sale.
The ESOP series
unknown node- What are ESOPs? ESOP meaning, vesting and tax in India – you are here
- Types of vesting: Time-based vs performance-based and vesting schedules
- Beyond ESOPs: RSUs, SARs, phantom stock and ESPPs
Key takeaways
The seven things worth remembering
- In India an ESOP is an Employee Stock Option Plan, which is a right to buy shares at a fixed price. It is not the American Employee Stock Ownership Plan, which is a trust based retirement structure.
- A grant is a promise. Vesting earns the right to buy. Exercise is the step where options actually become shares. Only the last of the three makes an employee a shareholder.
- Most Indian schemes carry a one year cliff followed by vesting over four years, with the exercise price fixed at the date of grant.
- ESOPs are not taxed at grant and not taxed at vesting. Tax is triggered twice: as a salary perquisite at exercise and as capital gains at sale.
- The perquisite is payable even though no shares have been sold and no cash has been received, which is why exercise timing matters so much in unlisted companies.
- The holding period for capital gains runs from allotment at exercise, not from the grant date.
- Vested options that are not exercised inside the exercise window simply lapse, which is one of the most common ways employees lose value they had already earned.
If you've joined a startup or growing company in India, chances are your offer letter mentioned "ESOPs" somewhere in the compensation section. For many employees, that is also where the clarity ends – the terms sound familiar but the mechanics rarely get explained well. And for employers, designing and communicating an ESOP scheme well is just as important as the legal paperwork behind it – it is often the difference between equity that genuinely motivates a team and equity that employees quietly discount. This guide walks through what an ESOP actually is, the vocabulary that comes with it, how the tax works at each stage and how the whole process unfolds over time – useful reading whether you are granting options or holding them.
What is an ESOP? ESOP full form and meaning
An Employee Stock Option Plan (ESOP) gives employees the option to buy a specific number of company shares at a predetermined price, once certain conditions have been met. It is important to note that an option is not the same as owning shares outright – it is a right to purchase shares in the future, not an automatic grant of equity today.
An ESOP is the right to buy at yesterday's price

The option only pays off if tomorrow's share price is higher than the price fixed today.
ESOP full form – a common point of confusion
In India, ESOP stands for Employee Stock Option Plan. In the United States, the same acronym usually refers to an Employee Stock Ownership Plan – a trust-based retirement vehicle that buys shares on employees' behalf, a completely different structure. If you are reading American articles about ESOPs while holding an Indian grant letter, this is almost always the source of the confusion. Everything in this guide refers to the Indian meaning: stock options.
Employers typically build ESOP schemes to:
- Attract talent without stretching fixed cash compensation, particularly in the early stages of a company's life.
- Align employees' long-term incentives with the company's growth and valuation.
- Improve retention, since most ESOP schemes are structured to reward employees who stay with the company over a period of years.
- Create a shared outcome at a liquidity event – a funding round, secondary sale, buyback, or IPO – so the people who built the value participate in it.
In India, ESOPs are governed primarily by the Companies Act, 2013 (Section 62(1)(b) read with Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014), with additional requirements under the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021 for listed companies and tax treatment defined under the Income Tax Act (Section 17(2)(vi) of the 1961 Act, carried into the Income Tax Act, 2025).
Key ESOP terms you need to know
Each term below appears somewhere in a real grant letter. Read yours alongside the list to work out what you actually hold.
Whether you are reading a grant letter as an employee or drafting one as an employer, the same handful of terms carry most of the weight. Click any term to expand it.
01Grant
The formal offer made by the company to an employee, specifying the number of options being awarded, the exercise price and the vesting schedule. The grant date marks the starting point of the entire ESOP timeline for that employee.
02Cliff period
An initial waiting period during which none of the granted options vest. Most ESOP schemes in India build in a 1-year cliff before any vesting begins. If an employee leaves before the cliff ends, they typically forfeit the entire grant.
03Vesting
The process by which an employee gradually earns the right to exercise their granted options, spread out over a defined period (commonly three to four years). Vesting can follow a straight-line schedule, a graded schedule, or be tied to specific milestones.
04Vesting conditions
The conditions that must be satisfied for options to vest. Continued employment is the baseline condition in most schemes, but employers are increasingly layering in performance-based conditions – individual targets, team goals, or company-level milestones.
05Exercise
The act of actually exercising your vested options by paying the exercise price, which converts them into shares. Vesting only gives an employee the right to buy – exercising is the step where that right becomes actual share ownership.
06Exercise price (strike price)
The pre-agreed price payable on each vested option to acquire one share, fixed at the time of grant. If the company's share value rises above this price by exercise, the difference is the employee's notional gain.
07ESOP pool
The block of shares a company sets aside specifically for employee grants, expressed as a percentage of fully diluted equity. Indian startups typically reserve between 5% and 15%, topped up at each funding round.
08Fair market value (FMV)
The value of one share on a given date. For listed companies it is the average of the opening and closing exchange price; for unlisted companies it must be certified by a registered merchant banker. FMV on the exercise date determines the employee's tax bill.
09Liquidity event / buyback
The moment employees can actually convert shares into cash – a company-run buyback, a secondary sale, an acquisition, or an IPO. Without a liquidity path, even well-designed ESOPs are discounted heavily by employees.
10Forfeiture & lapse
Forfeiture is the loss of unvested options, usually on exit. Lapse is the expiry of vested options that were not exercised inside the exercise window. Both are defined in the scheme document and both are where employees most often lose value without realising it.
11Exercise period
The window of time, after vesting, during which an employee is allowed to exercise their vested options. This window often shortens significantly if an employee resigns or is terminated – commonly to 30–90 days from the last working day.
How ESOPs work in India: the full timeline
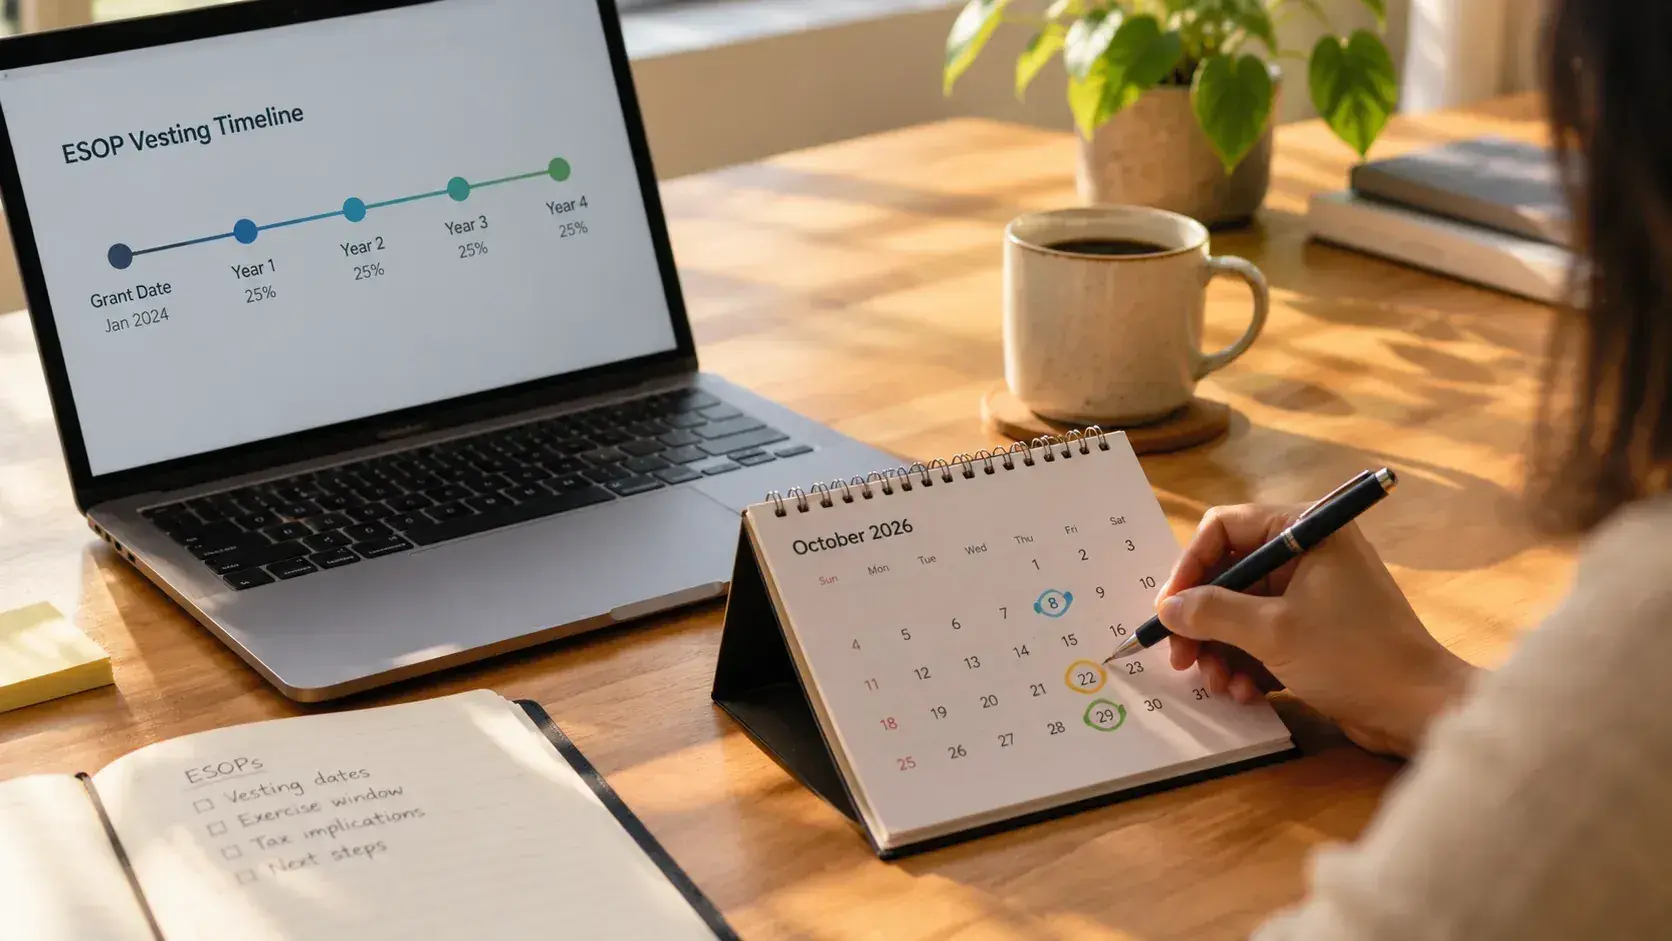
The vesting dates are the easy part to track. The deadline that catches people out is the exercise window after you leave.
Put together, these terms describe a journey that typically plays out over several years. Here is how a standard ESOP timeline looks in practice.
The ESOP lifecycle, grant to exercise

Based on a common one year cliff and four year vesting structure. Actual schedules vary by company and scheme.
Hover any milestone for detail
Worth noting
If an employee resigns or is terminated before the cliff, unvested and often even vested-but-unexercised options can be forfeited depending on the scheme's terms – which is why reading the exercise period and termination clauses in the ESOP scheme document carefully matters.
The table below is the whole lifecycle on one screen. The column that catches people out is the last one: three of the four stages create no tax at all, and the one that does arrives before any money has changed hands.
Stage | What happens | What the employee owns | Cash required | Tax event |
|---|---|---|---|---|
Grant | The company promises a fixed number of options at a fixed exercise price | A contractual promise | None | None |
Cliff | The first tranche becomes exercisable, at least one year after grant | The right to buy a portion | None | None |
Vesting | Remaining tranches become exercisable on schedule | The right to buy more | None | None |
Exercise | The employee pays the exercise price and shares are allotted | Actual shares | Exercise price plus perquisite tax | Perquisite, taxed as salary |
Sale | Shares are sold in a buyback, secondary or on exchange | Cash | None | Capital gains |
How are ESOPs taxed in India?
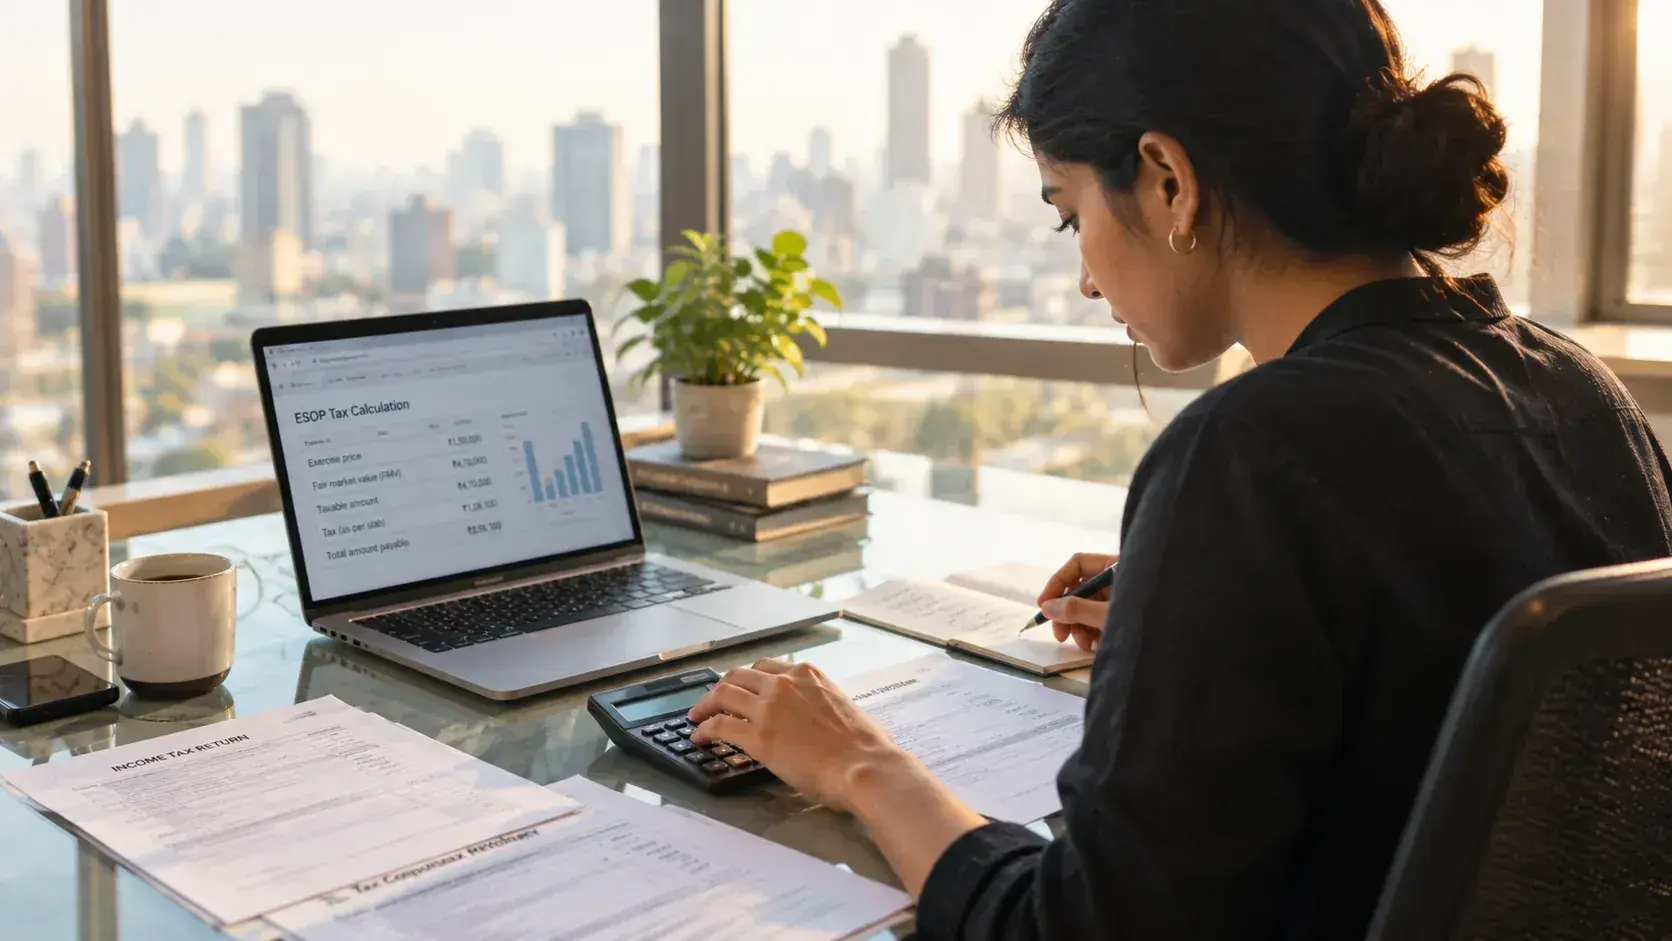
The perquisite is computed on the exercise date, usually well before any money has changed hands.
ESOPs are not taxed at grant and not taxed at vesting. Tax is triggered at two separate points and the gap between them is where most employees get caught out.
When tax is actually triggered

Two events, two different tax treatments. Neither happens at grant or at vesting.
Hover either tax point for detail
Stage 1 – perquisite tax at exercise
On the day you exercise, the difference between the fair market value of the share and the exercise price you paid is treated as a salary perquisite. It is added to your income and taxed at your applicable slab rate and your employer deducts TDS on it.
Perquisite value = (FMV on exercise date − exercise price) × number of options exercised
The uncomfortable part: this tax is payable even though you have not sold anything and have no cash in hand. For unlisted companies especially, employees can face a large tax bill on a paper gain they cannot yet monetise. Planning exercise timing around expected liquidity is the single most useful thing an employee can do here.
Stage 2 – capital gains at sale
When you eventually sell, the FMV already taxed at exercise becomes your cost of acquisition, so you are not taxed twice on the same gain.
Capital gain = sale price − FMV on exercise date
Share type | Long-term if held | Broad treatment |
|---|---|---|
Listed shares (sold on exchange) | More than 12 months from allotment | Long-term concessional rate with an annual exemption threshold; short-term gains taxed at the higher prescribed rate |
Unlisted shares | More than 24 months from allotment | Long-term rate without indexation; short-term gains taxed at slab rates |
Note: the holding period runs from the date of allotment (exercise), not from the grant date. A grant made four years ago and exercised last month has a holding period of one month, not four years.
The startup deferral
Employees of DPIIT-recognised eligible startups can defer the perquisite tax at exercise by up to 48 months, or until they sell the shares or leave the company – whichever comes first. This was introduced specifically to address the cash-flow problem above. Eligibility is narrow: the company needs both DPIIT recognition and an Inter-Ministerial Board certificate, and most recognised startups hold only the first. The compliance sits with the employer, so confirm it with your finance team rather than assuming it applies. Note also that the Income Tax Act, 2025 renumbered these provisions from 1 April 2026, so grant letters and board resolutions citing Section 192(1C) or Section 80-IAC should be refreshed to the current references before the next exercise event.
Filing: ESOP income cannot be reported on ITR-1. Salary plus ESOP capital gains means ITR-2, or ITR-3 if you also have business or professional income.
Tax rates and section numbers change with each Finance Act and the Income Tax Act, 2025 has renumbered several relevant provisions. Verify current rates and section references before acting.
The tax arrives before the money does. Every ESOP decision an employee makes is really a decision about that gap.
A worked example, end to end
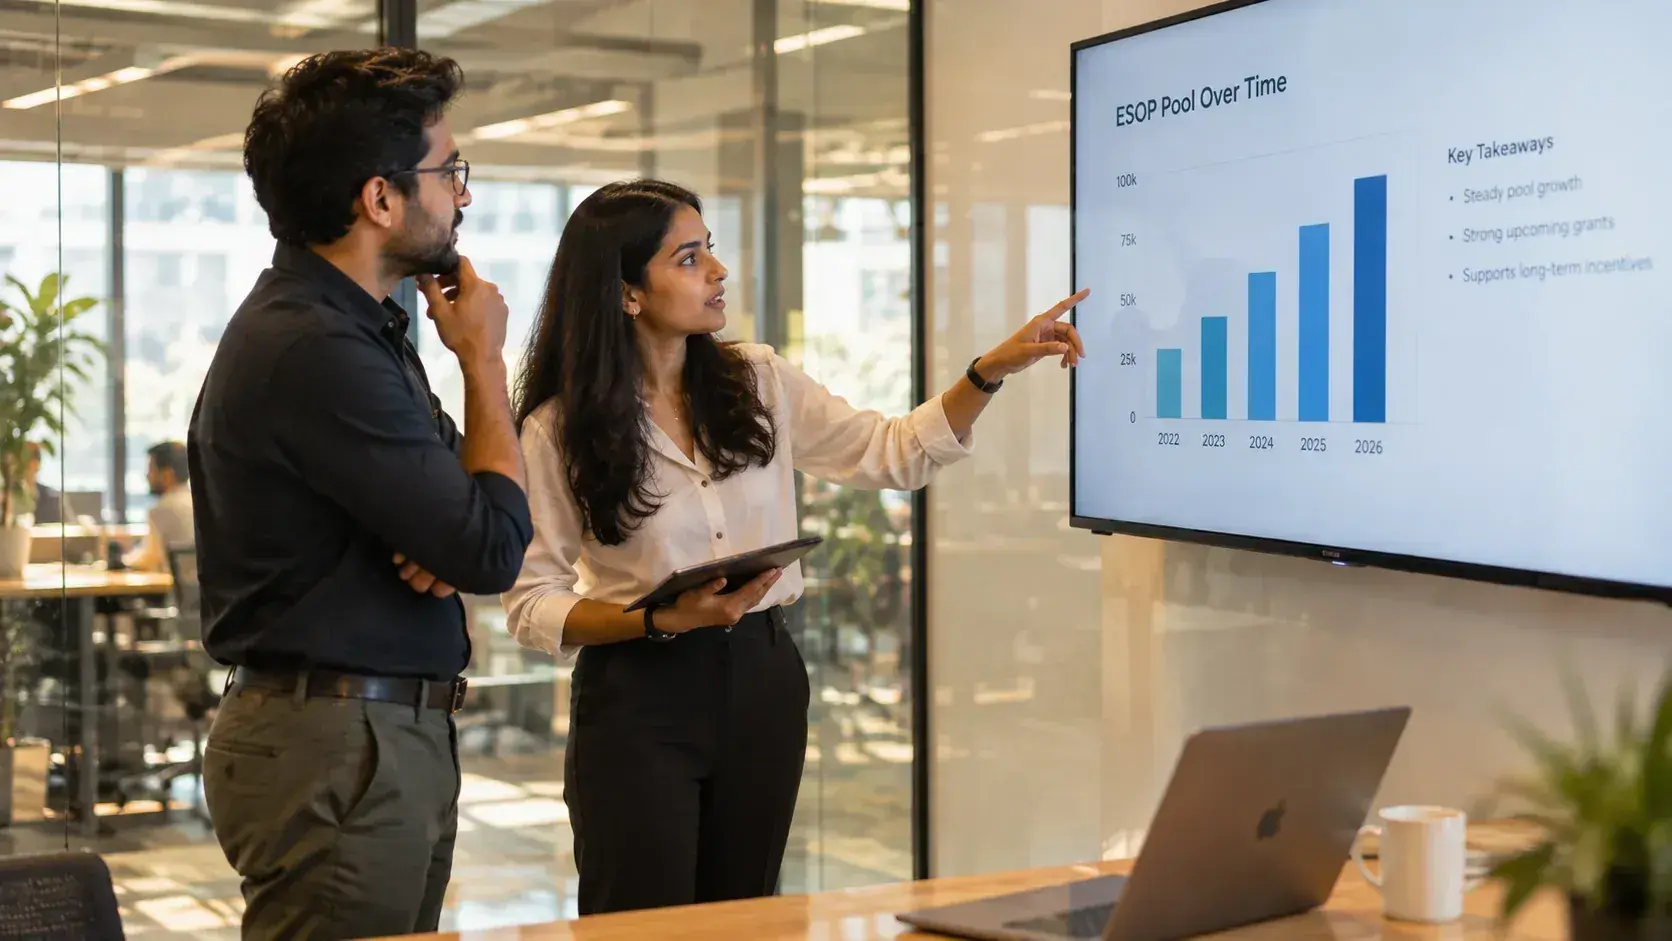
The chart on the screen is the company view. The five numbers below are the same grant seen from the employee side.
Priya joins a Bengaluru SaaS company in April 2022 and is granted 4,000 options at an exercise price of ₹50, with a one-year cliff and four-year vesting.
Priya's ESOP, in five numbers

Illustrative example. Figures follow the worked example in this section.
Hover any pillar to see the calculation
The lesson for employees: budget for the exercise cost and the tax on it. The lesson for employers: if your people cannot fund the exercise, your equity is not functioning as a reward – which is why exercise financing, cashless exercise and periodic buybacks are worth designing in from the start.
A grant letter that cannot answer eight plain questions is not a reward. It is an unpriced option on someone else's goodwill.
How big should an ESOP pool be?
Pool size, the grant letter and compliance records are the three documents an ESOP scheme is judged on in diligence.
Pool size is the question founders ask last and should ask first. The pool is carved out of the existing shareholders' ownership, so it is a real cost borne by the cap table rather than the profit and loss account. The ranges below reflect common Indian practice rather than any statutory limit; there is no legal cap on pool size.
Stage | Common pool range | What it is funding | Refresh pattern |
|---|---|---|---|
Pre-seed | 5 to 10 percent | The first handful of senior hires | Topped up at the seed round |
Seed to Series A | 10 to 15 percent | Broad-based grants across the early team | Investor-mandated top-up at each round |
Series B and later | 10 to 15 percent, replenished | Leadership hires and refresh grants | Annual refresh cycle |
Pre-IPO | Varies widely | Retention through the listing | Board-approved, often the larger part of new grants |
Two practical points. First, an option pool created before a funding round dilutes the founders rather than the incoming investor, which is why the pool size is negotiated as part of the term sheet rather than after it. Second, a pool that is exhausted at the moment you need to hire a senior leader forces a choice between going back to shareholders for an expansion and reaching for a cash-settled instrument instead.
What to check in your ESOP grant letter
- How many options, at what exercise price and what percentage of fully diluted equity does that represent?
- What is the cliff and what is the vesting schedule after it – annual, quarterly, or monthly?
- Is vesting purely time-based, or are performance conditions attached?
- How long is the exercise window while employed and how long after you leave?
- What happens on resignation, termination for cause, redundancy, death or disability?
- Is there any accelerated vesting on a change of control or acquisition?
- How is FMV determined and how often is it refreshed?
- Has the company ever run a buyback and is one planned?
What to check | What a good answer looks like | What should worry you |
|---|---|---|
Number and exercise price | A stated count, a stated price, and the percentage of fully diluted equity it represents | A rupee value with no share count, or no percentage disclosed |
Cliff and schedule | One year minimum, then a named cadence: monthly, quarterly or annual | Vagueness, or a cliff under twelve months |
Vesting conditions | Time-based, or a performance target stated as a number, a date and an owner | Discretionary vesting decided later by management |
Exercise window | A defined period while employed and a defined period after leaving | A window measured in days with no extension mechanism |
Leaver treatment | Named outcomes for resignation, cause, redundancy, death and disability | Silence, or a blanket forfeiture clause covering all exits |
FMV methodology | A stated valuation basis and a stated refresh frequency | Fair market value set at the board's discretion with no method |
Liquidity history | A past buyback, a tender offer, or a stated intention with a timeframe | No liquidity event ever, and no plan for one |
If the grant letter does not answer these, the scheme document should. Ask for it – you are entitled to read it.
How Tallect approaches ESOPs
ESOP administration that lives inside the rest of the reward picture
Tallect is a modular Total Rewards platform built by Total Rewards practitioners. The Equity module sits in the same system as compensation planning, benchmarking, bonus and sales incentives and benefits, so equity data lives next to the rest of the reward picture rather than in a standalone cap table tool.
The module is built around the mechanics in this guide. Cliffs, vesting schedules and exercise windows are configured once and tracked automatically. Fair market value refreshes, perquisite computation and audit ready reporting are handled in the platform, and every employee gets a live view of what they hold, what has vested and what it is worth.
2
tax events to plan for
1 yr
statutory minimum before vesting
5–15%
typical ESOP pool size
30–90
days to exercise after leaving
Frequently asked questions about ESOPs in India
What is the full form of ESOP?
In India, ESOP stands for Employee Stock Option Plan, a scheme giving employees the right to buy company shares at a fixed price after vesting. In the United States the same acronym usually means Employee Stock Ownership Plan, a different trust-based retirement structure. The two are frequently confused in search results, so check which country's meaning a source is using.
Are ESOPs taxed at grant or at vesting in India?
Neither. Tax is triggered first at exercise, when the difference between fair market value on the exercise date and the exercise price is taxed as a salary perquisite at your slab rate. It is triggered again at sale, when the gain over that fair market value is taxed as capital gains. Grant and vesting are not taxable events in India.
What happens to my ESOPs if I resign?
Unvested options are almost always forfeited and returned to the company's option pool. Vested but unexercised options usually carry a shortened exercise window, commonly 30 to 90 days from the last working day, after which they lapse entirely. The precise treatment is set in the scheme document, so read the leaver clauses before you resign rather than afterwards.
What is a typical ESOP vesting schedule in India?
A one-year cliff followed by vesting over four years is the most common structure, often 25 percent at the cliff and the remainder monthly, quarterly or annually thereafter. Only the one-year minimum is required by law under Rule 12. The four-year period and the 25 percent first tranche are market conventions that companies are free to change.
What is the difference between an ESOP and an RSU?
An ESOP is a right to buy shares at a fixed exercise price, so it only has value if the share price rises above that price and the employee must pay to exercise. An RSU is a promise to deliver shares at no cost once vesting conditions are met, so it retains value even if the price falls. RSUs are taxed at vesting; ESOPs at exercise.
How big should an ESOP pool be?
Common Indian practice sits between 10 and 15 percent of fully diluted equity for a company at seed to Series A, with smaller pools earlier and replenishment at each round. There is no statutory cap. The right number follows from how much of your hiring plan you intend to pay for in equity rather than cash, and it is negotiated at term sheet stage.
Can I sell my ESOP shares whenever I want?
Not in an unlisted company. Shares acquired on exercise are illiquid until the company creates a liquidity route: a buyback, a tender offer, a secondary sale to an incoming investor, or a listing. This is why exercise timing matters so much, since perquisite tax falls due at exercise whether or not any liquidity route exists yet.
Do ESOPs expire?
Yes. Options have a stated exercise period, both while employed and after leaving, and lapse if not exercised within it. Post-exit windows are typically 30 to 90 days in India. Options can also lapse if the underlying performance condition is never met or if the employee leaves before the cliff, in which case the whole grant is forfeited.
What is the exercise price and who sets it?
The exercise price, sometimes called the strike price, is the fixed per-share amount an employee pays to convert vested options into shares. It is set by the company at grant and stated in the grant letter. Indian companies have freedom to determine it in line with their accounting policies, so it can sit below the current fair market value.
How is fair market value determined for an unlisted company?
By a valuation carried out under the prescribed method, refreshed periodically rather than continuously. The fair market value on the exercise date is what drives the perquisite tax, so the refresh frequency matters directly to employees. A good grant letter states both the valuation basis and how often it is redone; many say nothing about either.
Can a startup defer ESOP tax for its employees?
Only if it holds both DPIIT recognition and an Inter-Ministerial Board certificate. Both are required, and most recognised startups hold only the first. Where the company qualifies, the perquisite tax at exercise can be deferred until the earliest of a sale of the shares, the employee leaving, or the end of the statutory deferral period.
Which ITR form do I use if I have ESOP income?
Not ITR-1. Salary income combined with capital gains from selling ESOP shares means ITR-2, or ITR-3 if you also have business or professional income. The perquisite is reported under salary and the capital gain separately. Section numbers and rates change with each Finance Act, so confirm the current position before filing.
Are ESOPs part of my CTC?
They should not be presented as though they are. ESOP value is contingent on vesting, on exercise, on a liquidity route and on the share price, none of which is guaranteed at offer stage. Good practice in India is to state the equity component separately from cash compensation so candidates can evaluate the two on their own terms.
Can promoters or independent directors receive ESOPs?
Generally not. Rule 12 excludes independent directors, promoters and directors holding more than ten percent of equity from ESOP eligibility. Recognised startups get a time-limited carve-out from these restrictions after incorporation. Companies wanting to reward excluded recipients usually use phantom stock or cash-settled stock appreciation rights instead.
What happens to ESOPs if the company is acquired?
It depends on the scheme document and the deal terms. Options may be assumed by the acquirer, cashed out at the deal price, or accelerated. Senior packages sometimes include acceleration clauses, either single trigger on the change of control alone or double trigger requiring a subsequent termination. Below senior level, acceleration is uncommon in India.
What is the difference between vesting and exercise?
Vesting is the point at which you earn the right to act on the promise made at grant. Exercise is the separate step of paying the exercise price so that shares are actually allotted to you. Vesting costs nothing and creates no tax. Exercise requires cash and triggers perquisite tax. Only exercise makes you a shareholder.
The bottom line
An ESOP is a right to buy shares at a fixed price once you have earned it. Five stages run from grant to sale, and only two of them matter financially: exercise, where you pay the exercise price and a perquisite tax on a gain you have not yet realised, and sale, where the money finally arrives. Indian law fixes very little of this. It requires one year between grant and first vesting, shareholder approval by special resolution, and a register of options. Everything else is written by the company.
That makes the grant letter the document that matters. Read it for the seven things that decide whether the grant is worth anything: the number and price, the cliff and schedule, the vesting conditions, the exercise window, the leaver treatment, the valuation method and the liquidity history. A company that answers all seven clearly is offering compensation. A company that cannot is offering a hope, and it is fair to price it that way.
This article is intended for general informational purposes only and does not constitute legal, tax, or financial advice. ESOP terms vary by company and scheme document and tax rates and statutory provisions change with each Finance Act; employees and companies should consult their specific scheme rules and a qualified professional for guidance on their individual circumstances.