ESOP vesting explained: Time-Based Vs Performance-Based Vesting
How vesting actually works in India: what has to happen for options to vest, how fast they pay out and what current market practice looks like.
The ESOP series
- What are ESOPs? ESOP meaning, vesting and tax in India
- Types of vesting: Time-based vs performance-based and vesting schedules – you are here
- Beyond ESOPs: RSUs, SARs, phantom stock and ESPPs
Key takeaways
The seven things worth remembering
- Vesting answers two separate questions: what has to happen for options to vest and how fast they pay out once they do. Treat them as independent design decisions.
- A grant is a promise, vesting earns the right to act on it and exercise converts that right into shares. Only exercise makes an employee a shareholder.
- Indian law requires a minimum of one year between grant and vesting. The four year total period and the 25 percent first tranche are market convention, not statute.
- Time-based vesting rewards tenure. It is simple, predictable and easy to run, but it pays the same whether or not the outcomes the company needs actually arrive.
- Performance-based vesting rewards outcomes, and only works when the target is specific, measurable and genuinely within the employee's influence.
- Linear, front-loaded, back-loaded and bullet schedules change the pace of payout, not the trigger. Back-loading strengthens long term retention.
- Most Indian companies default to simple time-based vesting for the majority of roles and layer performance conditions in selectively at senior levels.
Quick answer
What is ESOP vesting?
ESOP vesting is the process by which an employee earns the right to exercise stock options that were granted earlier, in stages rather than all at once. Indian law sets a minimum of one year between grant and first vesting. Everything after that floor, including the schedule and any performance condition, is a design choice the company makes.
Vesting is the most misunderstood word on an offer letter. It answers two separate questions that most explanations blur into one: What has to happen for options to vest and how fast they pay out once they do. This guide keeps those two questions apart, then looks at what Indian startups actually do in practice.
01What does it mean for an ESOP to vest?
A grant is a promise. Vesting is the process of that promise becoming real, in stages, rather than all at once.
STAGE 1
Grant
Company promises options at a fixed price. Nothing is owned yet.
STAGE 2
Vest
Employee earns the right to act on the promise, gradually.
STAGE 3
Exercise
Employee pays the exercise price and receives real shares.
Ananya is granted 2,400 options in January 2025, on a one-year cliff and four-year vesting. For twelve months she holds a promise and nothing more. At month twelve, 600 options (25 percent) vest at once; the rest vest monthly until January 2029. She has still not paid anything or received a single share; that only happens if and when she exercises.
This is also why an exit is treated in two halves. Vested options are usually hers to exercise, inside a limited post-exit window. Unvested options are forfeited back to the company's pool.
02Why vesting exists
Forfeiture on exit is written into the agreement at the start, not decided later. It is the clause worth reading twice.
Without vesting, a company could grant options to a new hire who quits in month two, having earned a permanent stake in everything the remaining team builds afterward. Vesting exists to stop exactly that: It protects the company from paying out ownership faster than value gets created and it gives the employee a written, upfront answer to what has to happen for those options to become real.
Worth noting
Vesting terms are set in the company's ESOP scheme document and are rarely renegotiated after a grant is issued. Read the cliff and schedule carefully at offer stage, not after.
03ESOP vesting rules in India: What The Law Requires
Before choosing a vesting structure, it helps to separate what Indian law actually mandates from what the market has simply settled into as convention. Most vesting design is contractual, but a few things are not negotiable.
Statutory requirements
- Minimum one-year vesting period: For unlisted companies, Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014, published by the Ministry of Corporate Affairs, requires a minimum of one year between the grant of options and vesting. This is the reason the one-year cliff is near-universal in India – it is a legal floor, not just a market habit. The SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021, last amended in December 2025, impose the same one-year minimum on listed companies.
- Shareholder approval: The scheme must be approved by shareholders by special resolution, with prescribed disclosures in the explanatory statement, including the vesting requirements, the vesting period and the maximum period within which options must vest.
- Eligibility limits: Permanent employees and directors qualify; independent directors, promoters and directors holding more than ten percent of equity are excluded. Recognised startups get a carve-out from these restrictions for a defined initial period after incorporation.
- Death and permanent incapacity: Options vest immediately on the death of an employee, passing to legal heirs or nominees. Permanent incapacity triggers immediate vesting too.
- Register of options: Companies must maintain a Register of Employee Stock Options (Form SH-6), with filings including Form MGT-14 for the special resolution and Form PAS-3 on allotment.
Recent regulatory updates worth knowing
- SEBI Regulation 9A (notified 8 September 2025): Founders who are reclassified as promoters in a draft IPO document may now retain and exercise options granted at least one year before the draft offer document is filed – closing a long-standing gap for IPO-bound startups.
- Sweat equity valuation (effective 2 January 2026): A December 2025 amendment replaced merchant bankers with IBBI-registered valuers for sweat equity valuations.
Law versus market practice
The one-year minimum before any vesting is a legal requirement. The familiar four-year total vesting period, 25 percent vesting at the cliff and monthly vesting thereafter are market conventions borrowed largely from international venture practice – companies are free to structure these differently, provided the statutory one-year floor is respected.
04Time-based vesting: Rewarding Tenure
Time-based vesting is a vesting model where options vest purely as a function of continued employment, with no performance condition attached at all. It works on a fixed clock: A cliff, then gradual vesting, regardless of what the employee has specifically delivered.
- How it works: A portion vests at the cliff, then the rest on a set monthly, quarterly or annual rhythm until the grant is fully vested.
- Why companies choose it: It solves a simple retention problem – keeping people around long enough to build and compound value – without needing a measurement system to run it.
- How it drives retention: Every unvested tranche is a reason to stay; leaving early forfeits value already "earned" by tenure.
- For the employee: Full predictability. Every vest date is known from day one and requires no judgment call from anyone.
- For the employer: Nothing to measure, no disputes to adjudicate, one schedule applies identically across a team.
Pros
- Simple to administer at scale, with no performance-tracking infrastructure required.
- Treats every employee on a comparable role transparently and consistently.
- Easy to explain in an offer letter, with no room for disagreement over whether a target was met.
- Nothing outside the employee's control – market conditions, a missed company target – can delay their vesting.
- Vesting value can be planned around with confidence, since every date is fixed in advance.
Cons and limitations
- Rewards tenure, not necessarily the business outcomes the company actually needs.
- Two employees can vest identically while contributing very differently – the core gap between rewarding tenure and rewarding performance.
- Offers no extra incentive to outperform once the schedule is locked in.
When it works best: Individual contributor roles and earlier-stage companies, where building a stable team fast matters more than measuring individual impact precisely. When it falls short: Senior or high-impact roles, where the company is really trying to buy a specific outcome rather than a specific tenure and a flat schedule pays out the same whether that outcome happens or not.
05Performance-based vesting: Rewarding Outcomes
Performance-based vesting ties some or all of a grant to a defined condition being met, rather than to time alone. A VP of Sales, for example, might vest a tranche each time annual recurring revenue crosses a set threshold, tying the payout directly to the outcome the role exists to drive.
- How it works: A tranche of options is earmarked against a specific, named condition; it vests only once that condition is verified as met.
- Company-level milestones: Revenue or ARR targets, a funding round, a valuation threshold.
- Individual milestones: An appraisal rating, a named deliverable.
- Role-specific outcomes: A product launch, entry into a new market, a technical milestone.
- Why companies choose it: Tenure alone does not capture what they are actually trying to reward, particularly for roles with significant, individually attributable impact.
- For the employee: A tighter link between contribution and payout, but exposure to conditions outside their control, such as a broader market downturn.
- For the employer: A stronger pay-for-outcomes story, at the cost of building and defending a measurement process.
Pros
- Directly aligns equity with the value the role is meant to create.
- Can motivate outsized effort toward a specific, high-priority outcome.
Cons and risks
- Only works if the target is genuinely within the employee's influence – a target set before a downturn, with no adjustment clause, can turn into resentment rather than motivation.
- Vague or subjective conditions are effectively unenforceable and tend to be disputed later.
- Adds real administrative weight: Someone has to measure, verify and sign off on every condition.
What makes a performance target fair and measurable
It survives being read by a stranger: A number, a date, a named owner. "Strong leadership" fails that test. "₹10 crore ARR by Q4" does not.
Which roles it suits: Current market data is consistent on this – performance vesting concentrates heavily among senior executives and specialised roles and stays rare for junior or individual contributor grants, where the cost of defending a fair target usually is not worth it.
06Time-Based Vs Performance-Based: Side By Side
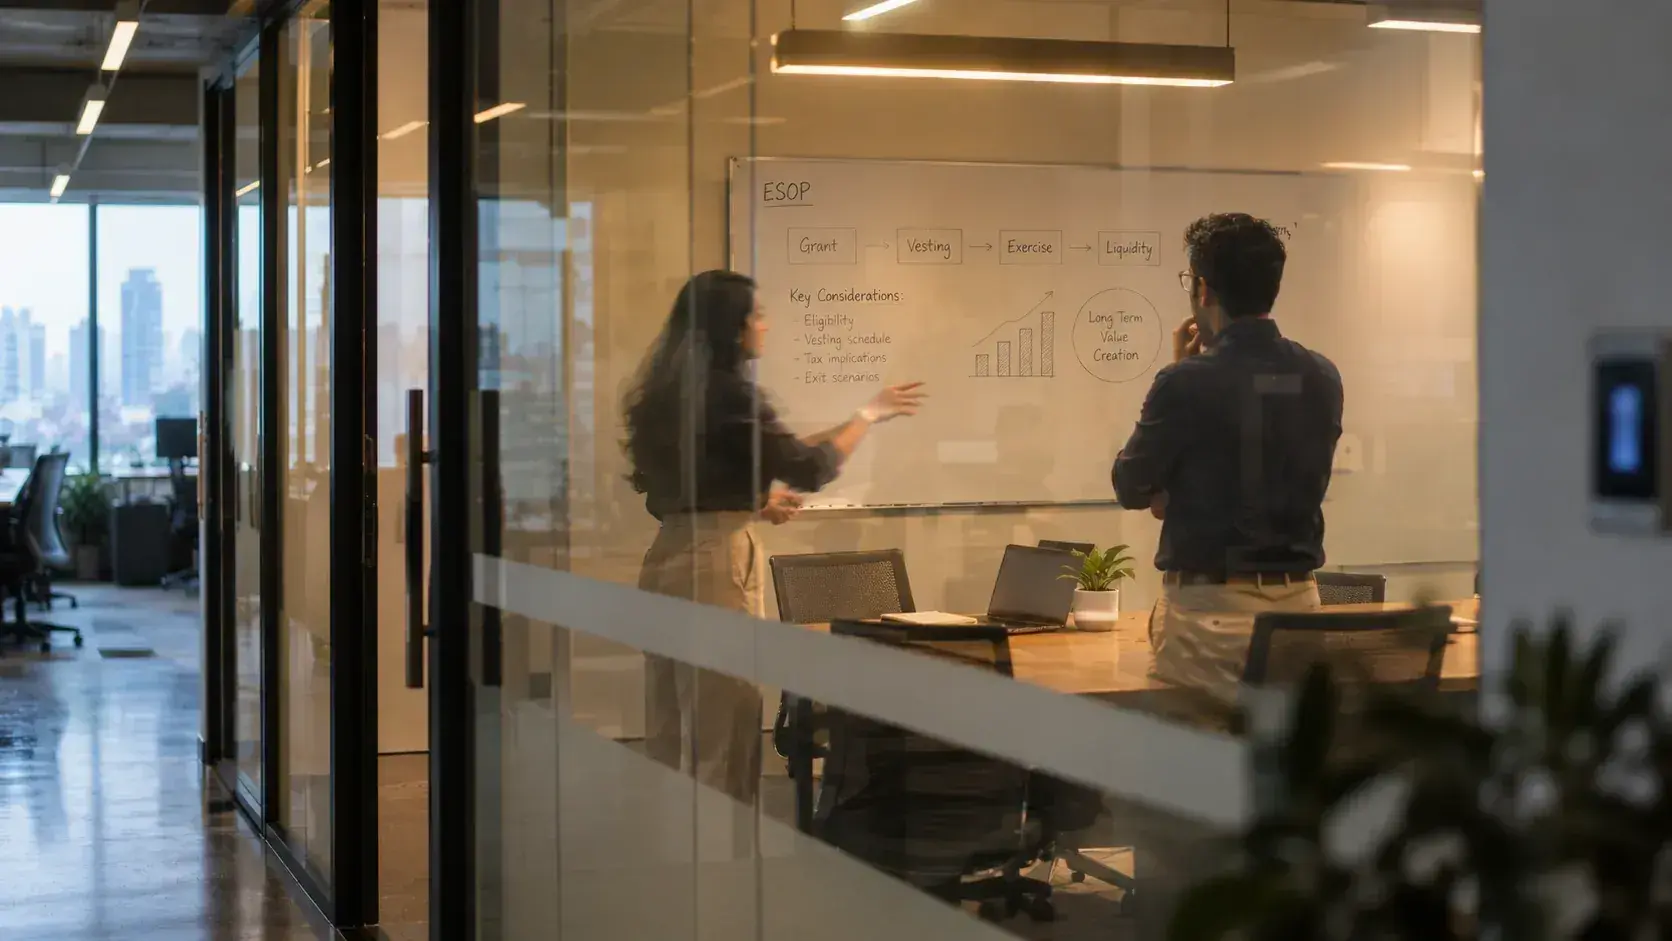
The two models answer different questions. One asks how long someone stayed, the other asks what they delivered.
These answer different questions. One asks how long someone stayed. The other asks what they actually delivered.
Read the table below by asking which risk you would rather carry: the risk of paying for tenure that did not produce an outcome, or the risk of a target that turns out to be unreachable for reasons nobody controlled.
Dimension | Time-based vesting | Performance-based vesting |
|---|---|---|
Trigger | Continued employment | Defined outcome or milestone |
Predictability | High, dates known upfront | Lower, depends on the target |
Admin load | Low | Higher, needs measurement and sign-off |
Employee risk | Tenure may not be rewarded fairly | Target missed for reasons out of their hands |
Company risk | Retains low performers as easily as high | A poorly built target demotivates instead of driving |
Dispute exposure | Near zero, the date either passed or it did not | Real, whenever the measure is subjective or contested |
Best for | Most roles, early-stage teams | Senior leadership, high-impact roles |
A vesting schedule is a promise about the future written by people who cannot see it. Design it so that a reasonable person could still call it fair three years from now.
07Designing a structure that works for both sides
The real design question is not "time-based or performance-based." It is where the overlap sits between what a company needs and what an employee can reasonably deliver.
Where a vesting structure has to land

Vesting works best inside the overlap, not at either extreme.
- A cliff that is punitively long protects the company but signals distrust from day one.
- Targets that shift after the fact, or stay vague, protect no one.
- Vested options with no path to liquidity are a number on a spreadsheet, not something an employee can plan around.
None of this means giving options away faster. It means designing pace and conditions both sides would sign again if asked today.
08The major vesting schedules: Explained
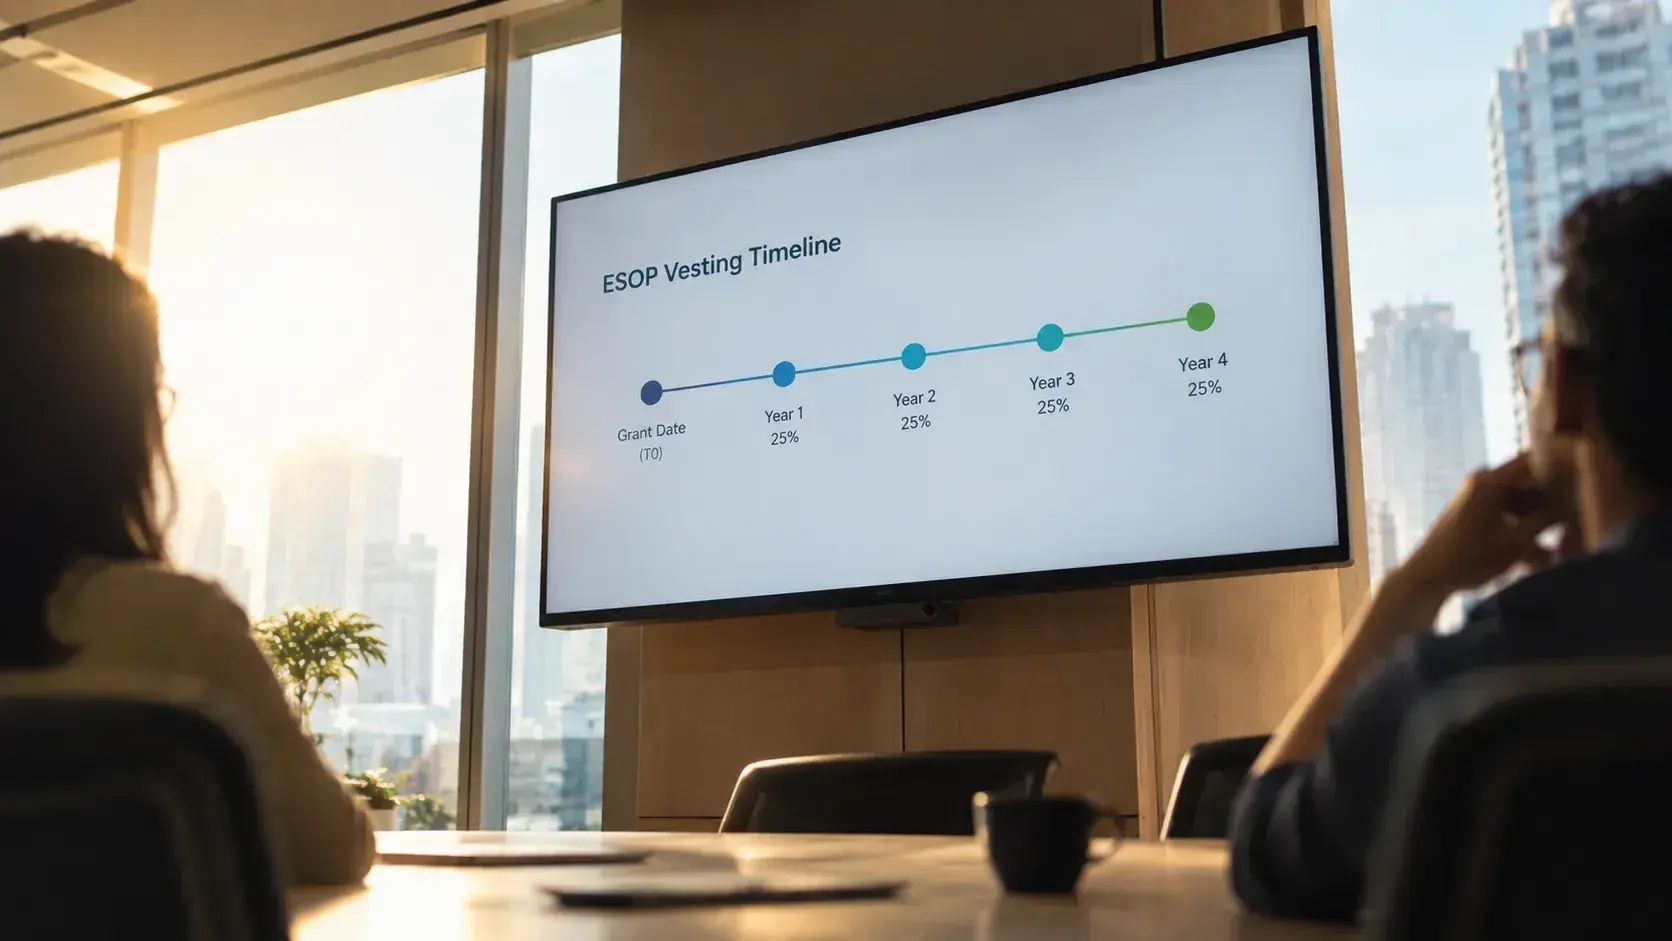
An even 25 percent a year is the default in India. The pace of payout is a separate decision from what triggers it.
Trigger type decides what releases vesting. Schedule decides how fast it pays out once it does – a separate axis entirely. A performance-linked grant can still pay out on a Linear schedule; a purely Time-based grant can still be Front-loaded or Back-loaded. Each chart below plots cumulative percentage vested by year, not the amount vesting in that year alone.
Four ways the same grant can pay out

Illustrative structures. Under Indian law no option can vest earlier than one year from grant.
- Back-loaded example: Roughly 10, 20, 30 and 40 percent across four years – slower to start than a flat Linear grant, but a materially stronger reason to stay through year four.
- Front-loaded trade-off: Useful for winning a competitive hire against a faster-paying offer, at the cost of a weaker pull once the largest tranche has already vested.
- Bullet vesting: Skips the gradual step entirely and shows up mostly in short, defined retention or M&A grants rather than standard multi-year schemes.
The India constraint on all four
Whichever shape a company picks, no option can vest earlier than one year from grant under Rule 12(6)(a) for unlisted companies, or the SBEB Regulations for listed ones. In practice this means a Front-loaded schedule in India front-loads from the one-year mark onward rather than from day one and a Bullet schedule must sit at least twelve months out.
A related but separate concept is acceleration, which changes a schedule on a trigger event such as an acquisition rather than its normal pace.
- Single-trigger: Options vest purely because the company was acquired.
- Double-trigger: Requires the acquisition and the employee losing their role afterward – generally investor-preferred, since single-trigger can leave an acquirer with a team that just vested out and has no reason left to stay.
Either form is uncommon outside individually negotiated senior packages.
Schedule | How it pays out | Retention pull | Typical use |
|---|---|---|---|
Linear | Equal tranches across the full period after the cliff | Even across the term | The default for most roles |
Front-loaded | Larger tranches in years one and two | Weakens sharply after year two | Short-horizon or turnaround hires |
Back-loaded | Larger tranches in years three and four | Strongest late in the term | Senior hires you need through an exit |
Bullet (cliff-only) | One tranche, everything at a single date | Concentrated on one day, then zero | Fixed-term projects and advisers |
09What Indian startups actually do
Current guidance from equity platforms and legal advisors serving Indian startups points to one dominant pattern for standard employee grants.
4 yr / 1 yr
Conventional total vesting period over the statutory 1-year minimum cliff
25%
Typical share vesting at the cliff; rest vests monthly or quarterly
10–15%
Common ESOP pool size, as a share of fully diluted equity
30–90 days
Typical window to exercise after leaving the company
- Performance vesting stays senior: CXOs and specialised leadership far more often than individual contributors, usually layered on top of a time-based base – effectively a Hybrid model.
- Stage matters: Pre-seed and seed companies mostly keep vesting simple and purely Time-based, prioritising speed of hiring over sophistication.
- From Series A onward: Performance triggers for leadership become more common, alongside refresh grants for employees whose original grant is now largely vested.
- Acceleration: Double-trigger structures are generally investor-preferred; both types remain the exception outside senior, negotiated packages.
Stage | Usual vesting model | Where performance conditions appear | Refresh grants |
|---|---|---|---|
Pre-seed and seed | Time-based only, four years over a one-year cliff | Rare, hiring speed matters more than measurement | Uncommon |
Series A to B | Time-based default | Leadership hires, layered on a time-based base | Starting, for early employees fully vested |
Series C and later | Time-based default, back-loading more common | CXO and specialised leadership as standard | Routine, on an annual cycle |
Pre-IPO | Time-based with negotiated acceleration at the top | Broad at senior levels, tied to listing milestones | Routine, often the larger part of the pool |
If a target cannot be written as a number, a date and a named owner, it is not ready to be attached to anyone's options.
10Before you accept a grant
Vesting terms are usually the least negotiated part of an offer, and the part that decides what the equity is worth.
A handful of questions decide most of a grant's eventual value. Ask them before signing, not after.
- Cliff length: Is it the standard one year, or something longer?
- Post-exit exercise window: Commonly 30 to 90 days – missing it is one of the most common ways employees lose value they had already earned.
- If performance-linked: How exactly is the target measured, who signs off and what happens if the target shifts because the market does?
- Liquidity path: Has the company run a buyback before and is one planned?
Vested options with no liquidity in sight are real on paper and largely theoretical in practice. A company with a well-designed scheme should answer all of this without hesitation, which is itself useful information.
Vesting only tells half the story. What happens to the two halves of a grant on the way out is set separately, in the leaver clauses, and that is where most disputes actually start. The table below shows the treatment Indian schemes most commonly apply.
Exit route | Unvested options | Vested options | Where it is set |
|---|---|---|---|
Resignation | Forfeited to the pool | Exercisable inside a short window, commonly 30 to 90 days | Scheme document |
Termination without cause | Usually forfeited, sometimes partially accelerated | Same window, occasionally extended by negotiation | Scheme document and offer letter |
Termination for cause | Forfeited | Commonly forfeited as well | Scheme document |
Redundancy | Forfeited unless the board resolves otherwise | Standard window, extension is a board discretion | Board resolution |
Death | Vest immediately, pass to heirs or nominees | Pass to heirs or nominees | Rule 12, overrides the schedule |
Permanent incapacity | Vest immediately | Retained by the employee | Rule 12, overrides the schedule |
Retirement | Scheme-specific, often forfeited | Often a longer window than resignation | Scheme document |
11Choosing the right model as a founder
Most schemes default to time-based vesting and add performance conditions only where impact is genuinely measurable.
Most companies do not need one philosophy company-wide. The strongest schemes default to simple Time-based vesting for most roles and add performance conditions selectively, only where impact is genuinely measurable and significant enough to justify the extra complexity.
Is the role senior or high-impact (CXO, specialised leadership)?
→
No: Default to standard Time-based, 4yr / 1yr cliff
If yes – is the outcome measurable and within the role's control?
→
No: Keep it Time-based even for senior roles
If yes – does the company want a stronger retention pull?
→
Yes: Hybrid – time-based base, performance tranche, consider Back-loading
- Use a specific number, a defined timeframe and a named owner for every target.
- If a target cannot be stated that plainly, it is not ready to be tied to anyone's options.
The goal is not the cleverest structure. It is one a reasonable employee would read, understand fully and work toward, without feeling it was designed to be unreachable, or too easy to mean anything.
12The four tests of a vesting schedule that works
A vesting schedule works when it survives four questions. Run any draft schedule through these before it reaches an offer letter. Most schedules that cause disputes later fail at test two or test three, and both failures are visible on paper at design time.
Test | The question | What failure looks like |
|---|---|---|
1. Legality | Does at least one year separate grant and first vesting, with shareholder approval on record? | A cliff under twelve months, or a scheme never put to special resolution |
2. Clarity | Could the employee restate the schedule accurately from memory after one reading? | Conditions that need a spreadsheet or a lawyer to interpret |
3. Control | Is every condition genuinely within the reach of the person carrying it? | A target that depends on a funding round, a market, or another team |
4. Horizon | Does the pace of payout match the period over which you actually need the person? | Front-loading a role you need for four years, or back-loading a two-year mandate |
Framework
The four tests, in order of how quickly they settle

Work down the list at design time, not at exit. Tests three and four are the two that need a conversation with the hiring manager rather than a lawyer.
The four tests are deliberately ordered. Legality is binary and settles quickly. Clarity and control are where judgment lives, and where most of the damage is done: a grant the employee cannot explain to their own family has already lost most of its motivational value, and a target outside someone's control converts an incentive into a lottery ticket. Horizon is the test founders skip most often, because the pace of payout feels like a detail until the person you most needed at month thirty has been fully vested since month eighteen.
Roadmap
One grant, from promise to shares

Illustrative layout based on the most common Indian structure. Figures shown are sample values for design purposes; your own cliff, tranche size and exercise window are set in the scheme document.
13ESOP vesting terms, defined
These are the terms that appear in almost every Indian scheme document and grant letter. If a grant letter uses a term that is not on this list, ask what it means before you sign.
Grant
The company's written promise of a fixed number of options at a fixed exercise price. Nothing is owned at grant.
Vesting
The process by which granted options become exercisable, in stages, once time or performance conditions are met.
Cliff
The initial period during which nothing vests. India requires a minimum of one year between grant and first vesting.
Exercise
The act of paying the exercise price to convert vested options into actual shares. Only exercise creates a shareholder.
Exercise price
The fixed per-share price set at grant, sometimes called the strike price, at which vested options can be bought.
Tranche
A defined block of options that vests on a single date or against a single condition.
Forfeiture
The return of unvested, and sometimes unexercised, options to the company pool when an employee leaves.
Exercise window
The limited period after leaving, often 30 to 90 days, in which vested options must be exercised or lapse.
Acceleration
A clause that vests options early on a trigger event such as a change of control or termination without cause.
Single trigger
Acceleration on one event alone, usually a change of control.
Double trigger
Acceleration only when two events coincide, typically a change of control followed by termination.
Option pool
The block of authorised shares reserved for employee grants, expressed as a percentage of fully diluted capital.
Form SH-6
The statutory Register of Employee Stock Options that Indian companies must maintain for every grant.
Special resolution
The 75 percent shareholder approval required to adopt an ESOP scheme under Section 62(1)(b) of the Companies Act, 2013.
How Tallect approaches ESOPs
Vesting logic configured once, tracked automatically
Tallect is a modular Total Rewards platform built by Total Rewards practitioners. The Equity module sits in the same system as compensation planning, benchmarking, bonus and sales incentives and benefits, so equity data lives next to the rest of the reward picture rather than in a standalone tool.
Every structure in this guide is supported directly. Linear, front-loaded, back-loaded, bullet, milestone-linked and hybrid schedules are configured once and then tracked automatically for every employee and every cycle, with cliff dates, exercise windows and forfeiture rules applied without manual reconciliation. Employees get a live view of what has vested and what is still to come.
1 yr
statutory minimum before vesting
4 yr
conventional total vesting period
25%
typical first tranche at the cliff
30–90
days to exercise after leaving
14Frequently asked questions about ESOP vesting
What is the minimum vesting period for ESOPs in India?
One year. Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014 requires a minimum of one year between the grant of options and vesting for unlisted companies, and the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021 impose the same minimum on listed companies. This statutory floor is why the one-year cliff is close to universal in Indian ESOP schemes.
What is the difference between time-based and performance-based vesting?
Time-based vesting releases options purely on continued employment over a fixed schedule. Performance-based vesting releases options only when a defined condition is met, such as a revenue target, a funding round or a product launch. Time-based vesting is predictable and simple to administer. Performance-based vesting ties the payout more closely to outcomes but requires measurable, clearly defined targets and a sign-off process.
What is a vesting cliff in an ESOP?
A cliff is the initial period during which no options vest at all. In India the cliff must be at least one year by law. An employee who leaves before completing the cliff typically forfeits the entire grant, which is why the first anniversary of a grant date matters so much. At the cliff, the first tranche vests in a single step, commonly 25 percent of the grant.
What is a typical ESOP vesting schedule in India?
A one-year cliff followed by vesting over four years is the most common structure, usually 25 percent at the cliff and the remainder monthly, quarterly or annually thereafter. Only the one-year minimum is law. The four-year total period and the 25 percent first tranche are market conventions borrowed from international venture practice, and companies are free to structure them differently.
What is back-loaded vesting?
Back-loaded vesting weights the larger tranches toward the later years of the schedule, so an employee might vest 10 percent in year one and 40 percent in year four. It strengthens long-term retention because the most valuable part of the grant is always still ahead. The trade-off is that it can read as ungenerous at offer stage, when candidates are comparing headline numbers.
What is front-loaded vesting and when does it make sense?
Front-loaded vesting delivers the larger tranches early, for example 40 percent in year one falling to 10 percent in year four. It suits short-horizon hires, turnaround mandates and roles where the value is created quickly. Its weakness is retention: once the bulk of the grant has vested, the schedule stops giving the employee any reason to stay.
What happens to my unvested ESOPs if I resign?
Unvested options are almost always forfeited and returned to the company's option pool. Vested but unexercised options usually carry a shortened exercise window, commonly 30 to 90 days from the last working day, after which they lapse. The exact treatment sits in the scheme document, so read the leaver clauses before resigning rather than after.
Can a company change my vesting schedule after the grant?
Not unilaterally in most schemes. Vesting terms are fixed in the scheme document and the grant letter, and changing them for an existing grant generally requires the employee's consent and, depending on the change, fresh shareholder approval. Companies can, however, set different terms for future grants. Always check whether your letter includes a variation clause.
Is performance-based vesting legal in India?
Yes. Indian law sets a minimum one-year gap between grant and vesting but does not prescribe what the vesting condition must be. Companies are free to attach performance conditions provided the scheme document discloses the vesting requirements and the maximum period within which options must vest, and provided shareholders approve the scheme by special resolution.
What is acceleration and should I ask for it?
Acceleration vests options early on a defined trigger, most often a change of control. Single trigger accelerates on the event alone. Double trigger accelerates only if the event is followed by termination. Acceleration is common for founders and senior executives and unusual below that level. It is worth asking about at senior offer stage, but rarely worth trading base pay for.
Do ESOPs vest if an employee dies or becomes permanently incapacitated?
Yes. Under Rule 12, options vest immediately on the death of an employee and pass to the legal heirs or nominees, and permanent incapacity triggers immediate vesting as well. This is one of the few places where the law overrides whatever the vesting schedule would otherwise have said, and it applies regardless of where the employee was in their schedule.
How many options should vest at the cliff?
There is no legal answer. Twenty-five percent of a four-year grant is the market default and works well because it maps cleanly to one of four years. Some companies vest less at the cliff and more later to strengthen retention. What matters more than the percentage is that the number is stated plainly in the grant letter and does not change afterward.
Does vesting trigger any tax in India?
No. Vesting itself is not a taxable event in India. Tax is triggered first at exercise, when the difference between fair market value and the exercise price is taxed as a salary perquisite, and again at sale, when the gain over that fair market value is taxed as capital gains. Employees of certain certified startups can defer the tax due at exercise.
Should a startup use monthly or annual vesting after the cliff?
Monthly vesting after the cliff is the more common choice because it removes the cliff-edge incentive to wait for an anniversary before resigning. Annual vesting is simpler to administer manually and is still used by smaller companies. Once vesting is tracked in software rather than a spreadsheet, the administrative argument for annual vesting largely disappears.
How do I know if my vesting schedule is fair?
Run it through four tests. Is it legal, meaning at least a one-year gap between grant and first vesting? Is it clear enough that you could restate it accurately from memory? Is every condition within your reach rather than dependent on a funding round or another team? Does the pace of payout match how long you plan to stay? A schedule that passes all four is defensible.
15The bottom line
Vesting is two decisions wearing one word. The first decision is what has to happen for options to vest: time served, an outcome delivered, or some combination of the two. The second is how fast the payout arrives once the trigger is met. Indian law constrains only the first twelve months. Everything else, including the four-year norm and the 25 percent first tranche, is convention that a company is free to rethink.
The practical answer for most Indian companies is unglamorous and correct: time-based vesting as the default across the organisation, with performance conditions added selectively at senior levels where the outcome is measurable and genuinely within the role's reach. Test every schedule for legality, clarity, control and horizon before it reaches an offer letter. A grant the employee can explain accurately to their family is worth more than a cleverer one they cannot.
This article is intended for general informational purposes only and does not constitute legal, tax or financial advice. Vesting structures, cliff periods and acceleration terms vary by company and scheme document; employees and companies should consult their specific scheme rules and a qualified professional for guidance on their individual circumstances.