How to Run a Pay Equity Analysis In-House
A step-by-step guide to running a pay equity analysis yourself: the data you need, how to build comparator groups, unadjusted versus adjusted gaps, root causes, remediation and communication.
Companies that wait for a consultant or a lawsuit to tell them where their pay gaps are tend to find out at the worst possible time. This is a step-by-step guide to doing it yourself, with the methodology, the data requirements, and the interpretation pitfalls that most internal teams miss.
A Glassdoor study found that 67% of job seekers consider workplace diversity when evaluating companies (source needed). A separate 2025 survey by Mercer put it more directly: 54% of employees said they would leave an employer they suspected was paying them unfairly compared to peers (source needed). And yet, when Payscale surveyed HR leaders the same year, 39% admitted they had not run a formal pay equity analysis in the previous 12 months (source needed).
The reason is almost always the same: they assume it requires a specialist, a large dataset, or an expensive consultancy engagement. None of those assumptions is true for an organisation with more than 100 employees and a reasonably clean HRIS.
Pay equity analysis is not a one-time audit. It is an ongoing diagnostic that tells you whether your compensation decisions, taken across hundreds of individual managers and thousands of individual salary conversations, are producing systematically fair or systematically unfair outcomes. The methodology is not complicated. What trips most in-house teams up is the sequencing and the interpretation, not the maths.
What a pay equity analysis is (and what it is not)
Most people conflate two very different numbers, and that confusion produces bad decisions in both directions.
Unadjusted pay gap: The raw difference in average or median pay between two groups, say women and men, without controlling for any other factors. This is the headline number you see in gender pay gap reports. It captures occupational segregation, seniority concentration, and representation gaps as well as any direct pay discrimination.
Adjusted pay gap: The remaining pay difference between groups after you control for factors that legitimately explain pay variation: role, level, location, tenure, and performance rating. This is the number that tells you whether two people doing the same job at the same level are being paid differently because of a protected characteristic.
A company can have a large unadjusted gap and zero adjusted gap. That means women are concentrated in lower-paying roles, which is a representation and pipeline problem, but direct pay discrimination is not present. Conversely, a company can have a small unadjusted gap and a significant adjusted gap hiding inside it, meaning pay decisions at the individual level are biased even though the aggregate looks clean.
You need to understand both numbers. But the adjusted analysis is the one that tells you whether your compensation process is fair. The unadjusted number tells you whether your workforce is equitable. Fix both, but do not confuse one for the other.
Before you start: the data you actually need
The most common reason in-house pay equity analyses go wrong before they begin is incomplete or inconsistently labelled compensation data. You do not need perfect data. You do need complete data on a defined set of fields for every employee in scope.
Data field | Source | Why it matters |
|---|---|---|
Base salary / fixed pay | HRIS or payroll | Primary variable in every analysis |
Total cash (base + variable) | Payroll | Captures bonus and incentive disparities separately |
Job title | HRIS | Starting point before you normalise roles into comparator groups |
Job family or function | HRIS or job architecture | Groups roles doing comparable work |
Level or grade | HRIS | Critical control variable in adjusted analysis |
Gender | HR records (self-declared) | Primary protected characteristic in most analyses |
Location / cost-of-living zone | HRIS | Controls for geographic pay differences |
Tenure in company | HRIS | Legitimate pay-explaining variable |
Tenure in current role | HRIS | Separates promotion lag from pay lag |
Performance rating (last cycle) | Performance system | Only include if ratings are systematically applied; biased ratings mask discrimination |
Hire source (external vs internal) | Recruiting or HRIS | External hires often come in above internal equivalents, creating structural gaps |
Full-time vs part-time status | HRIS | Always analyse on a per-hour or FTE-equivalent basis |
Pull all fields for a single date-in-time snapshot. Do not mix payroll runs from different months.
Performance ratings should only be included as a control variable if they are applied consistently across demographic groups. If your performance rating process itself is biased, including ratings in your adjusted analysis will suppress a real pay gap behind a biased input. Check your performance rating distribution by gender and ethnicity before deciding whether to include it.
Step 1: Define your scope
Who is in scope?
Decide upfront whether you are including contractors, part-time employees, and employees on leave. Most analyses cover permanent, active employees only. If your contractor population is large, run a separate analysis for them. Including them in the main analysis without FTE normalisation will distort the results.
Which pay elements are in scope?
Run the analysis on base salary first, then on total cash compensation, then on total direct compensation including equity. Each layer can reveal a different pattern. Some organisations have equitable base pay but biased bonus allocation. Some have equitable cash but inequitable equity grants. You will not see that if you only look at one pay element.
Which protected characteristics are in scope?
At minimum, run gender. If you have sufficient data volume and the characteristic is tracked in your HRIS, also run race and ethnicity. A general rule of thumb: you need at least 30 employees in any comparator group for the statistical results to be meaningful. Below that threshold, results can be driven by one or two individual salaries rather than a systemic pattern.
Step 2: Build comparator groups before anything else
This is the step most teams skip, and it is the single biggest source of inaccurate results.
The adjusted pay equity analysis compares pay within groups of employees doing comparable work. If your job architecture is inconsistent, those groups will be arbitrary, and the results will be meaningless.
Before running any numbers, normalise your job titles into a clean job family and level structure. For the purpose of a pay equity analysis, you need each employee assigned to a job family (a cluster of roles doing broadly similar work: Software Engineering, Sales, Customer Success, Finance) and a level (typically 1 through 5 or 6, from individual contributor entry to senior leadership).
A job family and level combination is your basic comparator group. The question you are asking inside each cell is: are employees in this family at this level being paid differently based on a protected characteristic, after controlling for tenure, location, and performance?
Note: If you have more than 40 distinct job titles and no consistent levelling structure, pause the analysis and spend a week normalising roles first. Running pay equity analysis on inconsistently labelled roles produces numbers that look credible but are not.
Step 3: Run the unadjusted analysis
Group all employees by the characteristic you are analysing, calculate median and mean pay for each group, and compute the gap as a percentage. Do this at three levels: company-wide, by job family, and by job family and level combined.
The distribution of where gaps appear tells you a lot about their nature. A large company-wide unadjusted gap that shrinks dramatically at the job family and level level suggests the problem is representation, not direct pay decisions. A gap that persists even within job family and level is a signal that the adjusted analysis will find something.
Report both mean and median. The mean is sensitive to outliers, especially in Sales where variable pay can be very high for a small number of high performers. The median gives you a more robust picture of where the typical employee sits.
Step 4: Run the adjusted analysis
The adjusted analysis uses multiple regression to estimate the pay difference associated with a protected characteristic after controlling for the other variables you have collected.
The model specification is: log(pay) = job family + level + tenure + location + performance (optional) + gender or other protected characteristic. Log of pay is used as the dependent variable rather than raw pay because pay distributions are right-skewed. Using log(pay) means the coefficients you get back are interpretable as percentage differences.
The coefficient on the protected characteristic variable is your adjusted pay gap. A coefficient of 0.04 on a female indicator variable means women earn approximately 4% less than men with the same job family, level, tenure, and location.
You do not need a statistician to run this. Excel's data analysis toolpak handles multiple regression. Python's statsmodels, R's lm() function, and most BI tools with a statistics module can do this in under 10 minutes once your data is clean.
The number your CEO will ask about vs the number that actually matters
When you present pay equity results internally, you will almost always be asked about the unadjusted gap first. "We have a 14% gender pay gap" sounds alarming and tends to dominate the conversation. The adjusted number, say 2.8%, sounds less serious and often gets treated as a reason not to act.
Neither reaction is right. The unadjusted gap reflects real inequality even if it is not caused by biased pay decisions, because it captures who is in which roles and at which levels. The adjusted gap tells you whether your pay process itself is unfair. Both need to be presented together, with a clear explanation of what each measures, or the wrong conclusions follow from both.
Step 5: Interpret the results without jumping to conclusions
A statistically significant adjusted pay gap does not automatically mean deliberate discrimination. It means your pay outcomes are producing a pattern that cannot be explained by the legitimate variables you controlled for. The cause could be deliberate bias, structural bias built into your processes, or a historical artefact nobody has cleaned up.
What you found | What it probably means | Where to look next |
|---|---|---|
Large unadjusted gap, small adjusted gap | Representation problem, not direct pay bias | Promotion rates, hiring pipelines, and role access by group |
Small unadjusted gap, significant adjusted gap | Pay process is biased even though aggregate looks clean | Starting salary offers, merit increase allocations, bonus decisions |
Large gap in one job family only | Localised problem: one manager, one team, or one period of external hiring | Specific hiring and increase decisions in that function over the past 3 years |
Gap concentrated in mid-levels | Promotion timing or starting salary compression at transition points | How pay is set at promotion versus at external hire for the same level |
Gap in base pay but not total cash | Variable pay is coincidentally compensating for base pay inequity | Whether variable pay allocation is itself equitable |
Gap disappears when performance removed from model | Performance ratings are correlated with the protected characteristic | Rating distribution by demographic group, calibration process, manager patterns |
Each finding points to a different root cause. Do not treat them interchangeably.
Step 6: Root cause analysis
Once you have a statistically significant adjusted gap, the regression tells you the gap exists. It does not tell you which decision point created it. The most common sources, in rough order of frequency, are starting salary decisions, merit increase compounding, and promotion lag.
Root cause | How it shows up in the data | How to confirm it |
|---|---|---|
Starting salary disparity | Employees hired within the same 12-month window into the same role and level show different starting pay by demographic group | Run the regression on starting salary rather than current salary for a 2-year hiring cohort |
Merit increase compounding | No gap in starting salary, but gap grows with tenure; longer-tenure employees show larger gaps | Plot the adjusted gap as a function of company tenure; a widening pattern confirms compounding |
Promotion lag | Gap concentrated at higher levels; one group spends more time at a given level before promotion | Run time-in-level by demographic group; significant differences confirm the mechanism |
Manager concentration | Gap driven by a small number of job families or teams; other parts of the business are equitable | Run manager-level analysis on merit increase allocations; high-variance managers are usually the source |
Hiring source premium | External hires come in above internal employees at the same level; if one group is more likely to be internal, they carry a structural disadvantage | Compare starting pay by hire source and level; if the external vs internal premium explains the gap, it is still a gap you need to fix |
Step 7: Design the remediation
Remediation means increasing the pay of employees identified as underpaid relative to their comparators. It never means decreasing the pay of employees at the top of the range. Pay equity remediation is upward only.
Tier the remediation by the size of the gap and the statistical confidence of the finding. Employees where the modelled gap is above 5% and the comparator group is large enough to be statistically robust are remediated first. Employees where the gap is smaller or the comparator group is thin are addressed in the next cycle, after a year of additional data collection has made the finding more reliable.
How much remediation is enough?
The goal is to get the adjusted gap across all comparator groups below a threshold you define as acceptable, typically below 1% or within the margin of statistical noise. Getting there in one cycle is rarely possible. Companies that do this well set a multi-year target, remediate the highest-confidence and largest gaps in cycle one, then re-run the analysis before every merit cycle to track movement and catch new gaps before they compound.
One thing that consistently surprises first-time practitioners: the total remediation cost is almost always smaller than expected. A company with 800 employees typically finds that 60 to 80 individuals drive most of the aggregate gap, and the total remediation budget is 0.3% to 0.8% of total payroll (source needed). The analysis cost, whether in-house time or consultant fees, usually exceeds the remediation cost in the first year.
Step 8: Document and communicate
Write a methodology note that covers: the analysis date, the employee population in scope, the exclusions and why they were made, the pay elements analysed, the control variables included and any that were considered and excluded, the statistical method used, the threshold for significance, and the criteria for remediation prioritisation. Without this, the next person who runs the analysis will make different choices, and you will not be able to compare results across years.
On communication: employees do not need to know the details of the methodology, but they do need to know that the analysis happened and what you found. The Edelman 2025 Trust Barometer found that 61% of employees want their employer to be transparent about pay practices, and that transparency on pay is one of the top three drivers of institutional trust (source needed). "We ran a pay equity analysis. We found a 2.1% adjusted gap. We are addressing it through targeted adjustments this cycle" is better than either silence or a lengthy technical explanation that few employees will read.
The tools you need (and what you can skip)
Tool | Best for | Limitations |
|---|---|---|
Excel (Data Analysis Toolpak) | First-time analyses, datasets under 500 employees | Manual, no auditability, easy to make errors on large datasets |
Python (pandas + statsmodels) | Repeatable analyses, auditability, integration with HRIS exports | Requires someone comfortable with code; outputs need formatting for non-technical stakeholders |
R (lm() function) | Teams with data science capacity; best statistical output formatting | Steep learning curve for HR teams without a data background |
Compensation platform with built-in analytics | Ongoing monitoring, integration with live pay data, stakeholder-ready reporting | Varies significantly by vendor; check whether the regression methodology is transparent or a black box |
Purpose-built pay equity software | Complex organisations, multiple jurisdictions, regulatory reporting requirements | Cost; often more than necessary for companies under 1,000 employees |
Skip the pay equity consultants for the initial analysis unless you have a legal matter already underway. The methodology is not complicated enough to justify the fees for a standard audit.
Common mistakes that skew results
Why most in-house pay equity analyses reach the wrong conclusion
The most common error is including too many control variables in the adjusted analysis. The more variables you add, the more variance you explain, and the smaller the adjusted gap becomes. This feels like progress but is often just statistical noise reduction. If you control for salary history from a previous employer, you may be controlling away a bias that your hiring process imported from a company that discriminated. The legitimate controls are role, level, location, and tenure. Performance can be included if the rating distribution is itself equitable. Everything else should be treated with suspicion.
The second most common error is running the analysis on inconsistent comparator groups. If "Senior Engineer" means L4 in one business unit and L5 in another, your comparator groups are contaminated and your results are not meaningful. Normalise first, analyse second, every time.
Frequently asked questions
How often should we run a pay equity analysis?
At minimum, once a year, ideally tied to your annual merit cycle so that findings can inform the current year's increase allocations. Companies in jurisdictions with pay transparency legislation, including several US states and the UK, should run it more frequently as they approach reporting deadlines. Running it only when a complaint arises is the most expensive version: you are always reactive and rarely have baseline data to show improvement.
Do we need a statistician to run this in-house?
No, but you do need someone who understands what a regression output means and what the control variable choices imply. An HR analyst with intermediate Excel skills and a willingness to learn basic regression can run a credible analysis. What you should not do is hand it to someone who will run the numbers without understanding what they are measuring, because the interpretation errors that follow are worse than not running the analysis at all.
What is an acceptable adjusted pay gap?
There is no universal standard, but most organisations target an adjusted gap below 1% across all comparator groups, which is within the typical margin of statistical noise for a well-specified model. Anything above 2% that is statistically significant at the 95% confidence level should be treated as requiring remediation. The UK Equality and Human Rights Commission has historically used 5% as a threshold for escalation in regulatory contexts (source needed), but internal practice should aim considerably lower than that.
Should we share pay equity results with employees?
Yes, at a high level. You do not need to publish the full regression output or disclose individual salary comparisons. What employees benefit from knowing is that the analysis happened, roughly what it found, and what action you are taking. Companies that communicate this clearly tend to see better retention scores among the employees whose pay was adjusted, and among the broader population who interpret the transparency as a signal of fair dealing. The risk of saying nothing is higher than the risk of saying something honest.
What if we find a gap but cannot remediate it immediately due to budget?
Document the finding and commit to a remediation timeline in writing, internally. Prioritise the highest gaps and the employees closest to natural decision points like promotion or role changes. Do not delay the analysis because you are worried you cannot afford to act on it: knowing where the gap is and addressing it partially is better than not knowing. Budget constraints are a reason to phase the remediation, not a reason to suppress the finding.
What is the difference between pay equity and pay parity?
Pay equity refers to the principle that employees doing the same or comparable work should be paid the same, regardless of protected characteristics like gender or race. Pay parity is often used interchangeably, but sometimes specifically refers to achieving equal representation across pay bands or levels, which is closer to what the unadjusted analysis measures. In practice, the two terms are used differently by different organisations. What matters more than the terminology is being clear about which question you are actually asking and analysing.
Can we run a pay equity analysis if our HRIS data is incomplete?
It depends on what is missing. If gender or ethnicity data is incomplete because employees have not self-declared, you can run the analysis on the population that has, provided that population is not itself a biased sample of the whole. If structural fields like job family or level are missing or inconsistently applied, you need to clean those up before the analysis is meaningful. A partial analysis on clean data is better than a full analysis on dirty data. Document every exclusion and its reason.
How do we handle roles where fewer than 30 employees are in the comparator group?
Small comparator groups present a statistical reliability problem: a single high or low salary can drive what looks like a gap. The standard approaches are to merge adjacent levels into a broader group (combining L3 and L4 in a small function, for example), to treat the cell as below the minimum threshold and exclude it from the quantitative analysis while flagging it for manual review, or to use a bootstrapped confidence interval to convey the uncertainty in the result. Do not ignore small groups entirely: a small comparator group can still surface an obvious and actionable disparity even if the regression output is not statistically robust.
Does the analysis cover only base salary or all forms of compensation?
Run it on all major pay elements separately: base salary, short-term variable or bonus, long-term incentives and equity grants, and total direct compensation. Each can reveal a different pattern. A company with equitable base pay can still have a significant gender gap in equity grants if the grant allocation process is less structured than the base pay process. Combining all elements into a single number before analysis obscures where the gap is originating, which makes remediation harder to design.
What do we do if performance ratings are themselves biased?
First, confirm the bias. Run a distribution analysis of performance ratings by demographic group. If ratings are significantly skewed, say women or employees from certain ethnic backgrounds consistently receiving lower ratings after controlling for level and function, then including ratings in your pay equity regression will suppress part of the gap you are trying to measure. The technically correct approach is to run two models: one with performance included and one without. The difference between the two coefficients on the protected characteristic variable represents the portion of the pay gap that is being mediated through biased ratings. That portion should be treated as part of the pay equity problem, not as a legitimate pay difference.
How do we prevent new pay gaps from opening up after we remediate?
Remediation fixes the stock of existing gaps. It does not automatically fix the flow of new ones. To prevent new gaps from opening, you need to address the processes that created them in the first place: structured salary bands for new offers so managers are not setting pay from scratch, calibrated merit increase pools with documented rationale for any deviation from the matrix, promotion processes that require demographic distribution review before finalising decisions, and an annual pay equity analysis cycle that catches compounding before it becomes entrenched. One-off remediation without process change produces a gap that re-emerges within two or three merit cycles.
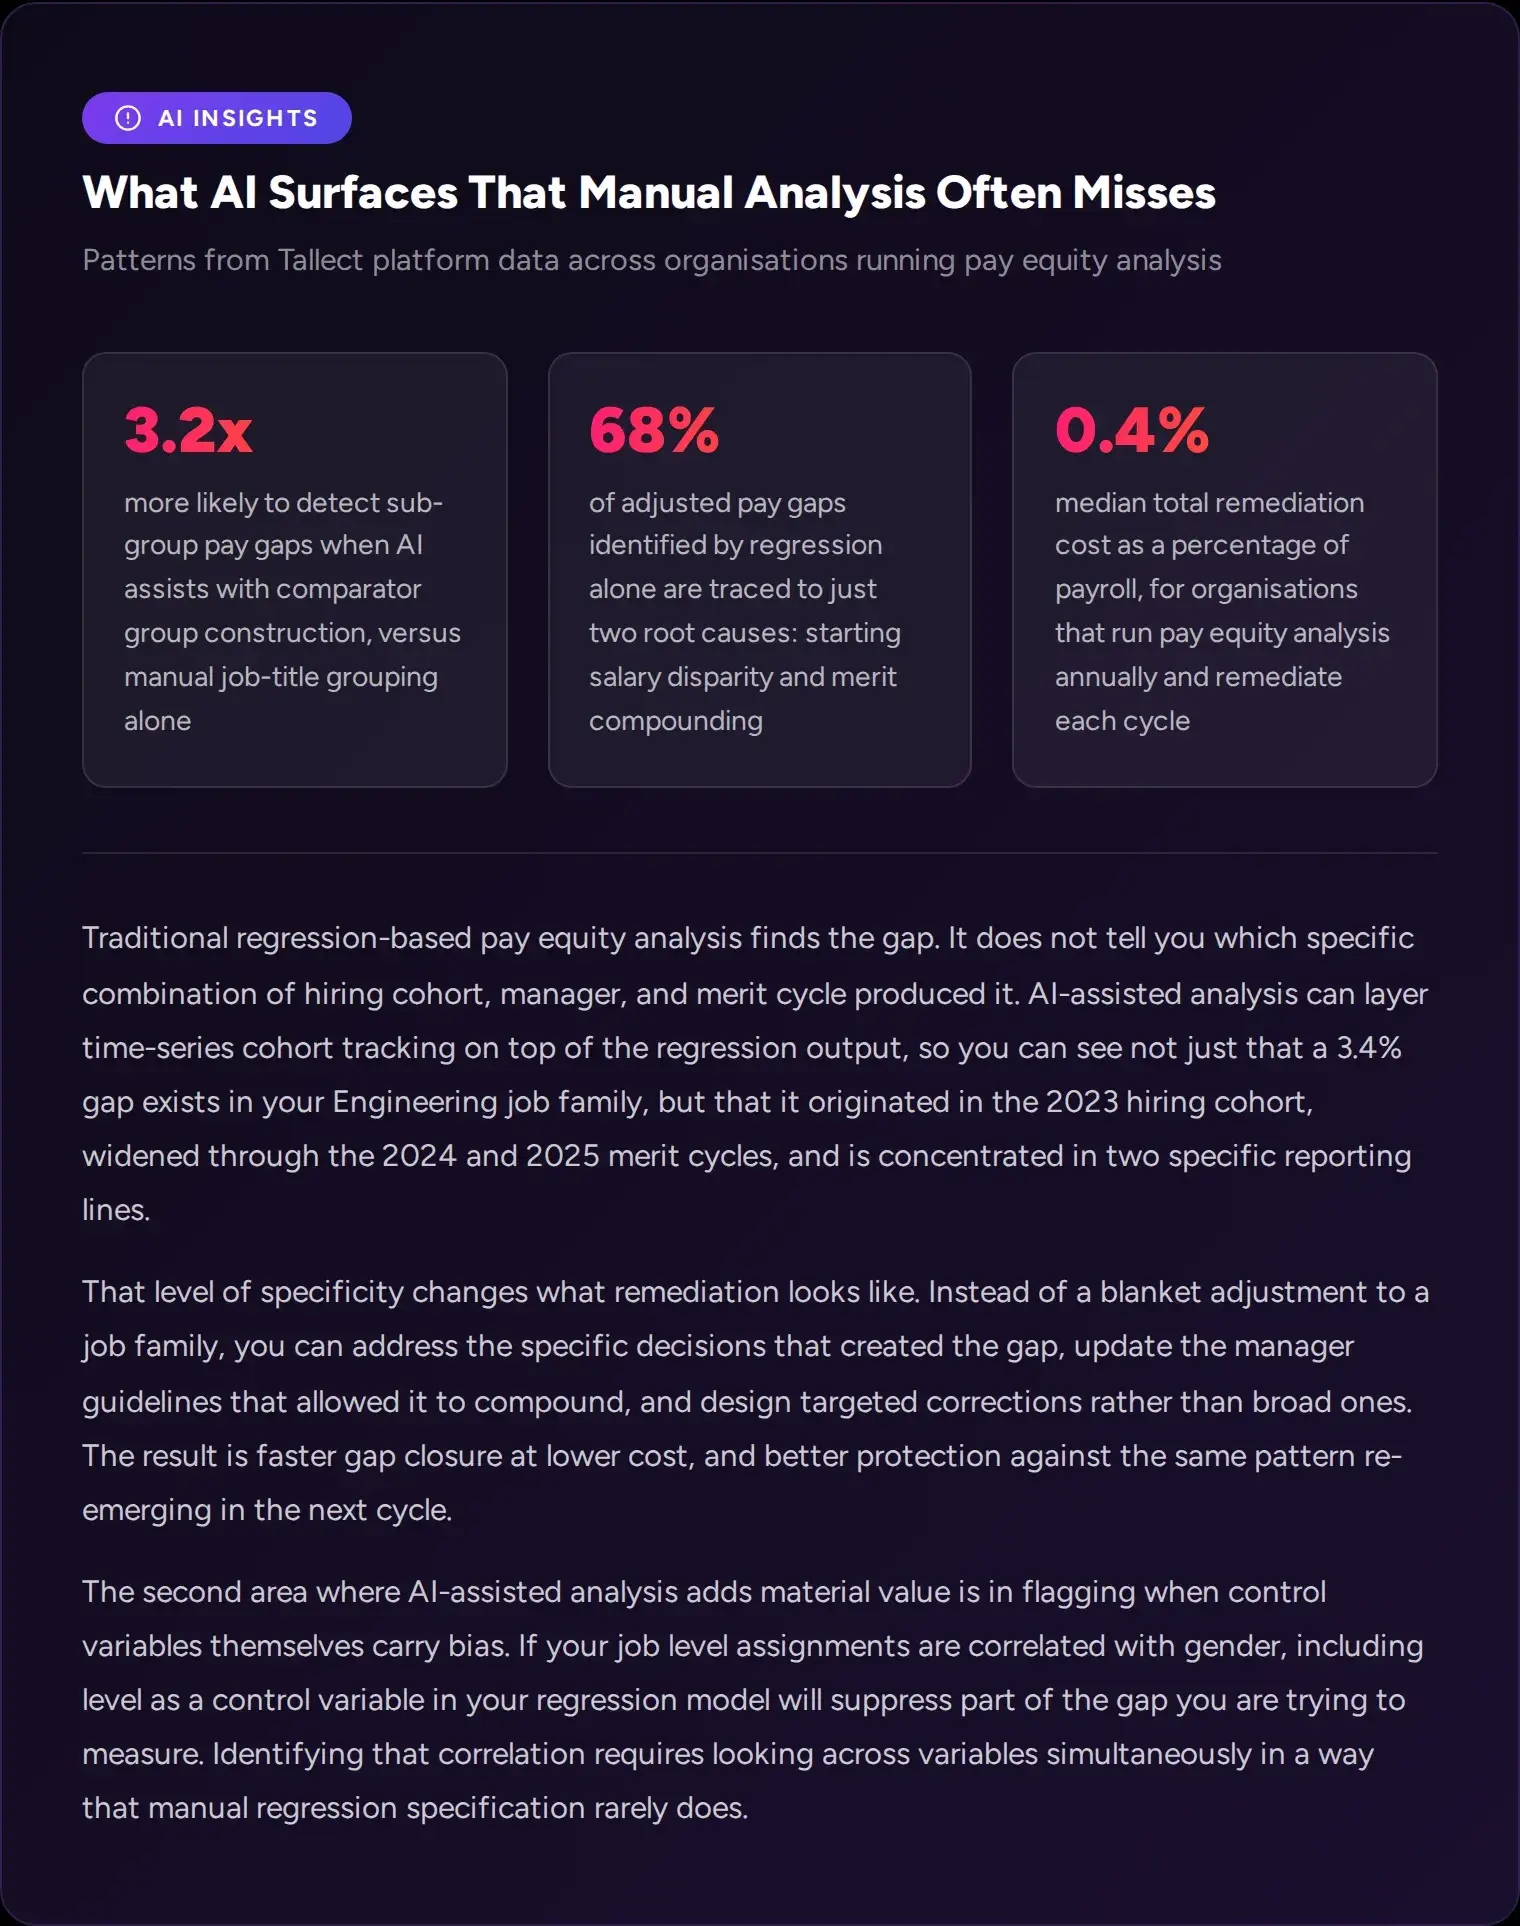
![Three statistics on AI-assisted pay equity analysis: 3.2x, 68% and 0.4%.]](/img/1920/75/api/media/file/pay-equity-analysis-cta.webp)